Archives 2026

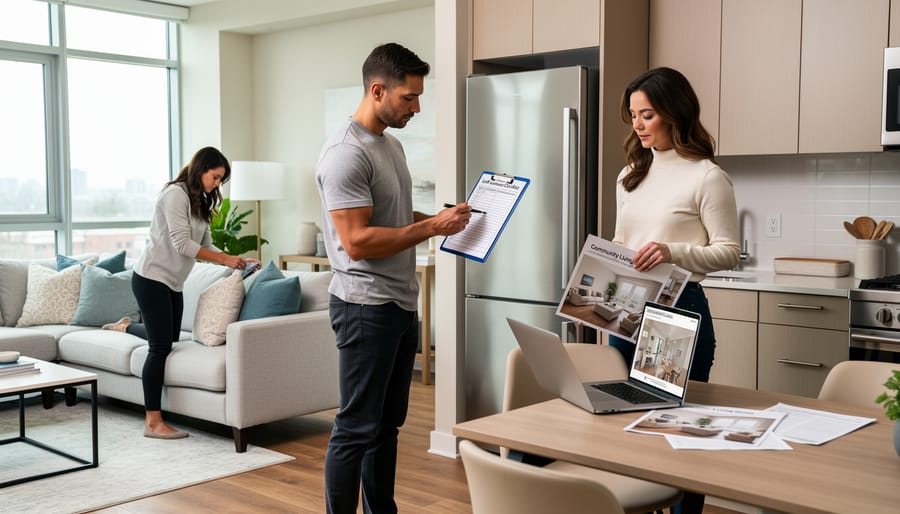
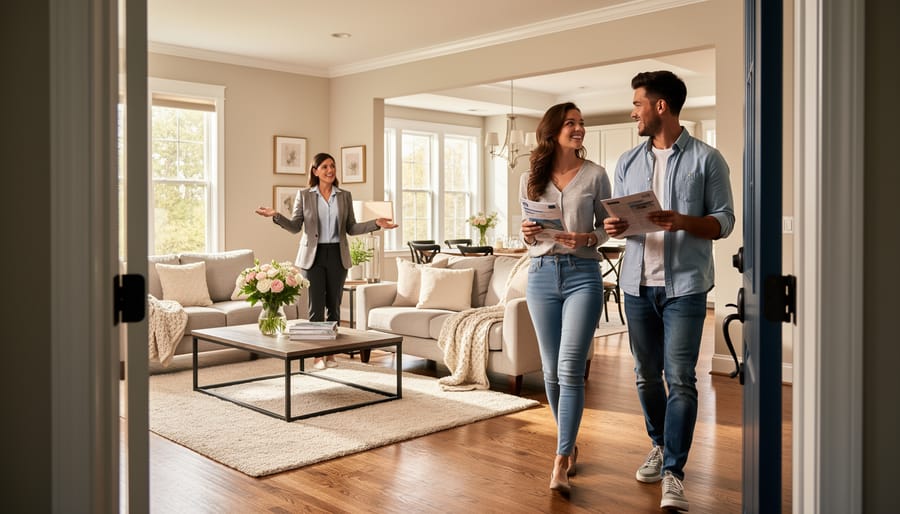
Marketing specialist and property manager collaborating inside a modern apartment leasing space, reviewing property details together.

How Property Management and Marketing Collaboration Transforms Vacancy Rates

Marketing property management works when promotion and operations function as a single system, not separate departments. The strategy reduces vacancy rates by an average of 15 to 30 percent while improving tenant quality through coordinated messaging that attracts the right renters and supports retention from the first contact through lease renewal.

The collaboration between marketing and property management teams creates a feedback loop that transforms how properties perform in competitive markets. Marketing professionals gain insights into tenant preferences, maintenance response times, and amenity usage patterns that shape more effective campaigns. Property managers receive pre-qualified leads and data-driven positioning strategies that fill units faster with residents who stay longer. This partnership matters especially in 2026, as rental markets across North America, Europe, and Asia-Pacific show increased sensitivity to online reviews, visual presentation, and community engagement.

Budget-conscious property owners often view marketing as an expense rather than an investment in operational efficiency. The reality proves different. Well-executed marketing reduces turnover costs, which typically run between one and three months’ rent per unit when accounting for vacancy periods, cleaning, repairs, and advertising. A coordinated approach addresses these costs at multiple points: professional photography and staging minimize days on market, targeted digital campaigns reach qualified prospects quickly, and tenant communication strategies improve satisfaction scores that drive referrals.

The framework outlined here demonstrates how property managers and marketing specialists can build workflows that serve both immediate leasing goals and long-term asset value, with particular attention to international markets where cultural nuances shape tenant expectations and budget allocation requires measurable returns.

Why Traditional Property Management Leaves Marketing as an Afterthought

Property managers carry a relentless operational load. They handle tenant complaints at midnight, coordinate emergency repairs, track rent payments, and ensure compliance with evolving regulations. Marketing, from this vantage point, becomes the thing you do when you finally have time, a necessary task rather than a strategic partner. The property manager’s calendar is dominated by leaking pipes and lease renewals, not brand positioning or visual storytelling.

Marketing teams, meanwhile, operate in a different world entirely. They think in aesthetics, emotional resonance, and visual narratives that stop scrollers mid-feed. Their expertise lies in lighting, staging angles, and the psychology of colour palettes. They know how to make a space look aspirational. What they often lack is ground truth: the operational realities that define how tenants actually experience the property day to day.

This structural divide creates predictable problems. A marketing team might showcase a stunning rooftop terrace without knowing the property manager has struggled for months to get residents to follow usage rules, creating noise complaints that drive turnover. Beautiful listing photos highlight gleaming appliances, but the copy says nothing about the responsive 24-hour maintenance the property manager has built as a competitive advantage. The messaging celebrates “luxury finishes” when prospective tenants in this neighbourhood actually care more about walkability and pet policies, information the property manager knows intimately but never shares.

Warning: This disconnect directly costs you money through extended vacancy periods (each empty week compounds), pricing misalignment with actual market demand, and brand inconsistency that confuses prospects and damages your reputation in tenant communities.

The result is properties that photograph beautifully but convert poorly. Listings attract the wrong inquiries because the marketing emphasizes features that don’t match what makes tenants stay. Showings disappoint because expectations set by aspirational imagery don’t align with the solid, well-managed reality the property offers. You’re marketing a lifestyle while managing a home, and when those narratives don’t converge, both vacancy rates and tenant satisfaction suffer. The property manager knows why people love living there; the marketing team knows how to tell that story. Keeping them in separate lanes wastes both skill sets.

The Strategic Framework: Where Management Insight Meets Marketing Execution

Property manager and marketing professional collaborate to photograph a professionally staged apartment interior
A staged apartment space is brought to life through joint work between property operations and marketing, showing how accurate presentation starts at the property level.

Translating Property Features into Lifestyle Benefits

Property managers know every detail about their buildings, the new HVAC system installed last quarter, the secured bike storage, the proximity to the metro station. But prospective tenants don’t rent features. They rent the life they imagine living.

This is where collaboration transforms vacancy rates. When property managers share their operational knowledge with marketing teams, those concrete details become emotional triggers. The new HVAC system isn’t about efficiency ratings; it’s about consistent comfort during work-from-home days and lower utility bills that free up budget for weekend adventures. Secured bike storage becomes an active lifestyle enabler for urban professionals who cycle to downtown offices. That metro proximity? It’s reclaimed time, mornings without traffic stress, evenings that start thirty minutes earlier.

Marketing specialists who understand tenant data can identify which features matter most to your target demographic. A property manager might mention updated kitchen appliances as a maintenance win; the marketing team recognizes it as the dinner-party centerpiece for young professionals building their social lives. This is where thoughtful presentation choices, from home glam decor that elevates listing photos to copy that speaks to aspirations rather than specifications, make the difference between inquiries and applications.

The most effective collaboration happens when property managers articulate not just what exists, but who it serves best. Marketing then builds narratives around those tenant profiles, transforming maintenance logs and amenity lists into stories prospective renters see themselves living.

Creating Marketing Materials That Reflect Property Reality

Marketing materials that promise luxury amenities, pristine conditions, and resort-style living create serious problems when the actual property tells a different story. Property managers know what happens next: frustrated showings, immediate rejections, and tenants who break leases early because reality didn’t match the photos.

Authentic marketing starts with honest conversations between management and creative teams before any camera equipment arrives. If the property has older appliances, worn flooring, or dated fixtures, your marketing should position these truthfully, perhaps emphasizing affordability, character, or upcoming renovation plans rather than pretending the property competes with new construction.

The styling choices matter tremendously here. A property manager dealing with a unit that serves budget-conscious tenants shouldn’t approve marketing photos featuring expensive furniture and high-end accessories that create false expectations. Instead, minimalist decor often works better, it showcases the space honestly while maintaining appeal, letting prospective tenants envision their own belongings without feeling misled.

This alignment protects everyone. Tenants arrive for showings with appropriate expectations, property managers waste less time on poor-fit prospects, and the eventual lease starts with trust rather than disappointment. Marketing materials should highlight genuine strengths, location advantages, responsive maintenance, community features, that property managers can actually deliver consistently throughout the tenancy.

Building Your Collaborative Workflow: From Listing to Lease

Staging of an apartment room alongside property maintenance work for a tenant tour
Careful staging and operational checks happen together, helping ensure the experience shown in marketing matches the tenant reality.

The most effective property-marketing partnerships don’t emerge when the “For Lease” sign goes up, they begin weeks earlier, with both sides contributing to a shared acquisition strategy.

Start your collaboration during the pre-listing walk-through, before any staging or photography happens. Property managers should bring maintenance records, recent tenant feedback, and knowledge of what’s drawn interest in similar units. Marketing specialists need this ground truth: knowing that the corner unit gets exceptional afternoon light or that prospective tenants consistently ask about pet policies shapes every subsequent creative decision. This initial meeting prevents the costly mistake of marketing features that don’t exist while overlooking genuine selling points only managers recognize from daily operations.

Staging decisions follow naturally when both perspectives inform the choice. A property manager knows whether the unit appeals to young professionals, families, or downsizing retirees based on location, layout, and rent point. Marketing translates this insight into visual direction, whether to style the second bedroom as a home office or nursery, how to arrange furniture to showcase flow, and which lifestyle signals resonate with the target demographic. When budget constraints limit physical staging options, managers can identify which rooms drive leasing decisions (typically living areas and primary bedrooms) so marketing resources concentrate where they matter most. Common design challenges like TVs and fireplaces competing for wall space need practical solutions that both showcase the space beautifully and acknowledge how tenants actually live.

Photography timing deserves joint planning. Schedule shoots after any needed repairs but before listing urgency forces compromises. Marketing teams need sufficient time to capture multiple angles, lighting conditions, and detail shots, while property managers must coordinate access without disrupting current occupants or rushing turnover work. A rushed photoshoot with poor lighting or incomplete staging wastes the entire marketing budget, images are your primary tenant acquisition tool.

Coordinate your showing strategy before the first inquiry arrives. Decide together which features the property manager emphasizes during tours (practical elements like storage, parking, maintenance responsiveness) and which aspects marketing materials have already established (lifestyle, aesthetics, neighbourhood advantages). This prevents redundancy and creates a cohesive experience where visual promise and operational reality reinforce each other. Both parties should review inquiry patterns weekly, if prospective tenants consistently ask questions your marketing didn’t address, adjust your materials rather than answering the same question fifty times.

Virtual and In-Person Staging: A Joint Decision

Choosing between virtual styling and physical staging isn’t a marketing decision alone, it requires property management input on timing, condition, and realistic budget constraints. The most effective approach combines management’s operational knowledge with marketing’s understanding of what converts prospects into applicants.

Physical staging delivers tangible impact when property managers can accommodate the logistics. A vacant three-bedroom home in a competitive market justifies the investment when management knows the property will show well for at least six weeks and can coordinate access for staging professionals. Physical staging works best for premium rentals where the target market expects move-in-ready presentation and where management has verified the property’s condition supports professional-grade photography and showings.

Virtual staging serves management needs when timeline or condition issues make physical staging impractical. A property requiring minor repairs before it photographs well, or one located remotely where coordinating physical staging creates scheduling challenges, benefits from virtual solutions. Property managers working across multiple locations particularly value virtual styling’s flexibility, designers can transform spaces digitally while managers handle operational priorities on-site.

Approach Budget Range Best Management Scenarios Timeline
Virtual Styling $50-200 per room Quick turnovers, remote properties, minor repairs needed, testing market positioning 2-5 days
Targeted Physical Staging $500-1,500 Key rooms only (living, master), moderate vacancy costs, standard rental market 1-2 weeks
Full Physical Staging $2,000-5,000+ Premium properties, high vacancy costs, showings scheduled regularly, 6+ week timeline 2-3 weeks

The hybrid approach often makes the most management sense: virtual styling for initial online listings to generate interest quickly, with the option to add select physical decor accessories or key furniture pieces if the property doesn’t generate showing requests within two weeks. This strategy keeps initial costs low while maintaining flexibility to invest more if market response demands it. Property managers should establish clear performance metrics with marketing teams, if virtual staging doesn’t produce qualified showings within a defined period, the collaboration shifts to physical staging with a revised budget allocation.

The International Perspective: Remote Collaboration for Property Marketing

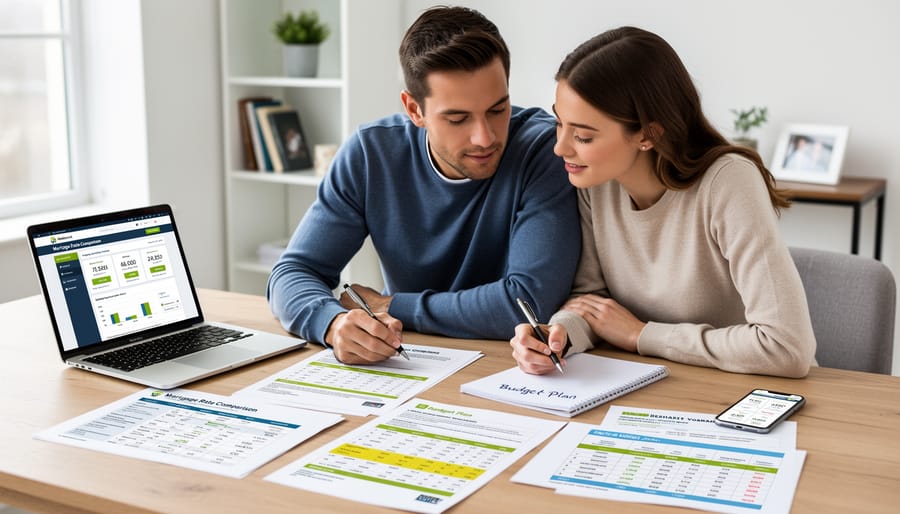
Remote collaboration between property management and marketing shown through a laptop and smartphone on a desk
Remote collaboration supports coordinated marketing and management decisions, keeping property presentation consistent across teams and locations.

Remote property marketing collaboration demands systems that work across time zones and languages without sacrificing quality or speed. Property managers overseeing portfolios in multiple cities, or working with international owners, need digital infrastructure that keeps marketing consistent while respecting geographic realities.

Start with a central digital asset library. Cloud storage platforms like Dropbox or Google Drive work, but specialized tools like Brandfolder or Bynder offer version control and approval workflows that prevent outdated floor plans or superseded photography from reaching prospective tenants. When your London office updates brand guidelines, your Singapore team should see those changes immediately, not three weeks later when someone forwards an email.

Time zone differences require asynchronous communication protocols. Instead of demanding real-time meetings, successful international teams rely on detailed briefs and recorded video walk-throughs. A property manager filming a two-minute property tour on their phone, highlighting specific features and condition notes, gives remote marketing teams context that dozens of photos cannot convey. Tools like Loom or Zoom recordings work well; the key is making feedback visual and specific.

Establish decision-making authority clearly. Define which choices require consensus (brand positioning, target tenant profiles) versus which the local team can make independently (showing schedules, minor styling adjustments). Ambiguity about approval chains kills momentum when properties sit vacant.

Consider language carefully. If your properties serve international tenants, marketing materials should feel locally relevant rather than obviously translated. Work with native speakers in target markets, not just for language accuracy, but for cultural nuances in how you present amenities, neighborhood benefits, and lifestyle positioning. A collaborative approach respects local expertise while maintaining brand consistency.

Measuring Success: Marketing Metrics Property Managers Should Track

Most property managers track when a unit fills, but few measure how marketing drives that outcome. The metrics that matter sit at the intersection of marketing effectiveness and management priorities, where creative decisions become business results.

Days on Market (DOM)
The total time from listing publication to lease signing, revealing how quickly your marketing attracts qualified tenants. A DOM consistently above market average signals messaging misalignment or presentation problems, not just market conditions.
Inquiry-to-Showing Conversion
The percentage of initial contacts that convert to scheduled property tours, measuring whether your marketing sets accurate expectations and attracts genuinely interested prospects. Low conversion suggests your visuals promise something your property doesn’t deliver.
Showing-to-Application Rate
How many tours result in rental applications, indicating whether the in-person experience matches the marketed promise. Strong marketing creates high showing-to-application rates because qualified prospects arrive already convinced.
Marketing Cost per Lease
Total marketing investment divided by signed leases, providing the true cost of tenant acquisition. This metric justifies higher-quality staging or photography when it demonstrably reduces vacancy periods.
Tenant Source Attribution
Tracking which marketing channels (listing sites, social media, referrals, signage) generate leases, allowing strategic budget allocation toward proven performers rather than assumptions about where tenants come from.

Beyond immediate leasing metrics, marketing quality influences retention. Properties presented authentically during marketing create satisfied tenants who experienced what they expected, tenants more likely to renew and refer others. Track how marketing vintage (the campaign that attracted them) correlates with lease renewals at twelve months. Properties that consistently attract tenant referrals signal marketing that resonated deeply enough to inspire word-of-mouth.

The strongest indicator of marketing-management collaboration? Declining time-to-lease across your portfolio while tenant quality improves. When both trends move favourably, you’ve found the balance between attractive presentation and operational reality.

Budget Allocation: Investing in Marketing as Property Management

The most expensive marketing decision a property manager makes is choosing not to market at all. Every day a unit sits vacant costs between $50 and $200 in lost rent, depending on your market, making even a modest marketing investment profitable if it fills the property one week faster.

Start by calculating your true vacancy cost: monthly rent divided by 30 equals your daily loss. If you’re losing $80 per day, spending $500 on professional photography and virtual staging pays for itself in six days. This reframing transforms marketing from a discretionary expense into an insurance policy against prolonged vacancies.

Budget tiers break down logically across property types. For units under $1,500 monthly, allocate $300-$500 per listing toward professional photography, basic virtual staging, and multi-platform listing distribution. Mid-range properties ($1,500-$3,000) justify $800-$1,500 for enhanced photography, room-specific staging, drone footage if applicable, and targeted social media promotion. Luxury properties above $3,000 monthly warrant $2,000+ investments including video walkthroughs, comprehensive physical or virtual staging, and premium listing placements.

The highest-ROI investment isn’t the flashiest option, it’s professional photography. Quality images reduce average days on market by 30-50% across all price points. Virtual staging comes next, particularly for vacant units where prospective tenants struggle to visualize space potential. Social media advertising ranks third, extending reach beyond standard rental platforms.

Track your marketing spend against days-on-market reduction and rental rate achieved. Properties marketed comprehensively often command 5-8% higher rents while filling faster, creating compounding returns. Budget what vacancy actually costs you, not what feels comfortable to spend, and your marketing decisions become straightforward risk management rather than hopeful expenditure.

The vacancy crisis facing property managers in 2026 isn’t solved by better locks or faster maintenance response times alone. It’s solved when operational excellence meets strategic marketing, when the team managing your property understands tenant psychology as deeply as they understand lease terms.

Properties that fill quickly and retain quality tenants share a common thread: management and marketing work as integrated functions, not separate departments fighting for budget scraps. The manager who knows which amenities drive renewals informs the marketer who crafts listing copy that attracts ideal prospects. The stylist who understands your target demographic collaborates with the manager who screens applications. This partnership creates properties that don’t just look appealing, they attract tenants whose needs align with what you’re actually prepared to deliver.

The financial case is clear. Every week a unit sits vacant costs more than most marketing investments. But beyond filling vacancies faster, collaboration improves tenant quality, reduces turnover, and positions your properties as premium options worth higher rates.

Stop treating marketing as the thing you do when you have a problem. Start building relationships with partners who speak both languages, who understand that successful property presentation requires management insight and creative execution working in concert, not competition.

Wide view of a warmly lit, partially furnished living room interior with a sofa and coffee table styled for planning different interior looks.

Designing Before You Buy: A Style-by-Style Guide to Virtual Staging and Furniture Planning

2 ott 2026 · @Sara Interior Design Lover

Introduction: The Room You Can’t Yet See

I write about virtual staging software, and most of what I publish is aimed at real estate agents trying to sell empty homes. But the longer I spend with this technology, the more convinced I am that its most interesting audience is not agents at all. It is people who care about interiors: homeowners planning a redesign, renters trying to make a small apartment work, boutique designers pitching a concept to a client, and anyone who has ever stood in an empty room wondering whether a sofa will fit.

This guide is written for that audience. It explains what virtual staging is, how it can be used as a planning tool rather than a sales tool, and how to use it to test the major interior design styles before spending money on furniture. It also covers the practical side of furniture planning, the measurements and clearances that make a room work, and how to brief a virtual stager so you get images that are useful rather than merely pretty.

I was reading an Esay about Furniture History on Reuters News (find it here) and was Inspired to write here about the Future of Furniture Planning.

A quick note on sources and honesty. I am not an interior designer, and I don’t claim design credentials. The style descriptions below summarize widely documented design history and conventions. The measurements are common rules of thumb used across the interior design and furniture industries; treat them as starting points and always measure your own space. I don’t include external links, but where I reference a specific idea or person, I name them so you can look them up.

What Virtual Staging Is

Virtual staging software and AI Interior App (basically This) is the digital addition of furniture, rugs, lighting, art and accessories to a photograph of a real space. The result is an image that shows how the room could look furnished, without any physical furniture being moved.

In real estate, the purpose is to help buyers imagine living in an empty home. In interior design, the same technology does something more useful: it lets you test decisions before you commit to them. You can see a mid-century sofa against your actual walls, in your actual light, at the actual scale of your room, then swap it for a deep Scandinavian sectional and compare the two.

There are three broad ways virtual staging is produced today.

Human-made 3D staging. A designer or 3D artist reconstructs the room’s geometry from your photo, places modeled furniture in a matching virtual scene, renders it with simulated lighting and composites it into the photograph. This is slower and costs more per image, but it produces accurate scale, believable shadows and precise control over exact pieces.

AI virtual staging. Generative AI tools estimate the room’s layout from a single photo and synthesize furniture directly into the image in seconds. They are fast and inexpensive, and they are excellent for exploring styles quickly. Their weakness is control: they may invent furniture that does not exist, ignore scale, or quietly alter fixed features of the room such as windows or flooring.

Hybrid services. Many providers now use AI for a first pass and human editors for corrections, which combines speed with better accuracy.

For design planning, the distinction matters. AI tools are ideal for the early, exploratory phase: which style suits this room? Human-made or hybrid staging is better for the decision phase: will this specific sofa, at this specific size, work in this specific corner?

Why Designers and Homeowners Should Care

Interior design has always relied on visualization. Designers sketch, build mood boards, draw floor plans and, increasingly, produce 3D renderings. Virtual staging adds something those tools often lack: it places the proposal inside a photograph of the real room, with its actual light, proportions, windows and quirks.

That has three practical benefits.

First, it reduces expensive mistakes. A sofa that looks perfect in a showroom can overwhelm a small living room. A rug that seemed generous online can float awkwardly in the middle of the floor. Seeing a proposal in the real room catches many of these problems before purchase.

Second, it makes style decisions concrete. Words like “Japandi” or “transitional” mean different things to different people. A staged image of your own room in each style turns an abstract conversation into a visual comparison.

Third, it helps people agree. Couples, roommates and design clients often disagree about style without realizing they are imagining different things. A set of staged images gives everyone the same reference point.

Furniture Planning Fundamentals

Before choosing a style, it helps to understand the principles that make any furnished room work, and then to arrange things you can just use tools such as Collov, Apply Design or also BoxBrown virtual staging software for realtors with ai model delivers photorealistic staging (reference: Strikingly.com) used by many professionals for the Sale here that leverage proprietary model training to generate realistic, fully furnished room designs in seconds like with Stucco and Similar Platforms. Style is the vocabulary; planning is the grammar. A beautifully styled room with poor circulation or badly scaled furniture still feels wrong, and virtual staging exposes those problems quickly.

Scale and proportion

Scale is the size of furniture relative to the room; proportion is the size of pieces relative to each other. A low, deep sectional can make a room with high ceilings feel grounded, while the same piece in a small room with low ceilings can make it feel crowded. A tiny side table next to an oversized armchair looks like an afterthought.

When you review a staged image, use fixed features as rulers. A standard interior door is commonly around 80 inches tall in the United States, and window sills, outlets and baseboards give additional reference points. If a sofa back appears taller than a window sill that you know is 30 inches off the floor, the staging may be exaggerating its size.

Circulation and flow

Circulation is how people move through a room. A useful rule of thumb is to keep main walkways around 36 inches wide where possible, and secondary paths no narrower than roughly 24 inches. In a living room, the distance between a sofa and a coffee table is commonly set between about 14 and 18 inches, close enough to reach a drink and far enough to walk past.

Good staging respects these paths. Poor staging blocks doorways with armchairs, pushes dining chairs into walkways or places a bed so that one side is unreachable. These errors are easy to miss in a beautiful image and very hard to live with in a real room.

Focal points

Most rooms have a natural focal point: a fireplace, a large window, a built-in, a view or a feature wall. Furniture planning usually starts by orienting the main seating or the bed toward that focal point. When a room lacks one, a large piece of art, a statement light fixture or a bold headboard can create it.

Ask your stager to identify the focal point in each room and arrange the furniture around it. If you disagree with their choice, that disagreement is itself useful, because it reveals how you actually want to use the space.

Zoning

Open-plan spaces need zones: a living area, a dining area, perhaps a reading corner or a workspace. Zones are defined by rugs, lighting, the backs of sofas and changes in furniture grouping, not by walls. Staging is particularly valuable for open plans because it shows whether the proposed zones feel distinct or simply cluttered.

Rugs

Rug sizing is one of the most common mistakes in real rooms and in virtual staging. A frequently used guideline for living rooms is that at least the front legs of the sofa and chairs should sit on the rug, so that it connects the seating group rather than floating in the middle. Under a dining table, the rug is commonly sized to extend about 24 inches beyond the table edge on each side, so chairs stay on the rug when pulled out. Under a bed, a rug that extends well beyond the sides and foot of the bed usually looks more intentional than one hidden beneath it.

Lighting layers

Designers often describe lighting in three layers: ambient light for general illumination, task light for activities like reading or cooking, and accent light to highlight art or architecture. Virtual staging can show floor lamps, pendants and table lamps, but be aware that many staged images simply brighten the photo rather than modeling the real effect of new fixtures. If lighting matters to your decision, ask your stager to show fixtures switched on in a darker version of the photo.

Visual weight and balance

Visual weight is how heavy a piece looks, not how much it weighs. Dark colors, solid bases and bulky forms read as heavy; light colors, exposed legs and open frames read as light. A room feels balanced when visual weight is distributed rather than concentrated on one side. Leggy furniture is a common tool for making small rooms feel larger, because seeing floor beneath a piece reads as space.

Measuring before staging

Virtual staging is only as accurate as the information behind it. Before commissioning images for planning, measure each room’s length, width and ceiling height, the positions and sizes of windows and doors, radiators and vents, and the locations of outlets and switches. Share these measurements with your stager. Human stagers can use them to scale furniture correctly; with AI tools, you will need to check results against them yourself.

A Style-by-Style Guide, Part One: The Modern Family

The sections that follow describe major interior styles, where they come from, what defines them, and how to plan furniture and brief a virtual stager for each. Styles overlap, and real rooms often blend two or three. Treat these as reference points rather than rules.

Mid-Century Modern

Origins. Mid-century modern refers broadly to design from roughly the mid-1940s to the late 1960s, associated in the United States with designers such as Charles and Ray Eames, George Nelson, Eero Saarinen and Florence Knoll, and in Scandinavia with figures such as Arne Jacobsen and Hans Wegner. Its roots include the Bauhaus and the broader modernist movement’s interest in function, new materials and mass production.

Defining features. Clean lines with gentle organic curves, tapered legs, low profiles, warm woods such as walnut and teak, molded plywood and fiberglass, and a mix of natural and graphic elements. Color palettes often pair warm wood with mustard, olive, teal, burnt orange or crisp white.

Furniture planning. Mid-century pieces tend to be low and leggy, which suits smaller rooms and lower ceilings. Because sofas are often lighter in scale than modern deep-seat designs, you may need more pieces to fill a large room, such as a lounge chair, a pair of side chairs and a credenza. The credenza or sideboard is a signature piece; place it along a long wall or beneath a window, with art or a lamp above.

Briefing a stager. Ask for a low-profile sofa with tapered legs, a walnut credenza, a classic lounge chair silhouette, a sputnik or globe pendant, and a geometric or solid rug. Specify that the room should not become a period set; a few authentic-feeling pieces mixed with contemporary basics often feel more livable. Avoid asking for specific branded designs by name if you are using AI tools, as results tend to be inconsistent; describe shapes and materials instead.

Scandinavian

Origins. Scandinavian design developed across Denmark, Sweden, Norway and Finland and gained international attention in the 1950s. It emphasizes functional, democratic design, light-filled interiors suited to long northern winters, and natural materials. Designers such as Alvar Aalto and Hans Wegner are closely associated with it. The Danish concept of hygge, often translated as a cozy, contented atmosphere, is frequently linked with Scandinavian interiors.

Defining features. Light woods such as oak, ash and birch; white or pale grey walls; simple, functional forms; textiles in wool, linen and sheepskin; restrained color with occasional muted accents; and an emphasis on daylight.

Furniture planning. Scandinavian rooms prioritize openness and light, so keep window walls clear and avoid heavy window treatments in staging. Furniture tends to be modest in scale with exposed legs. Layer texture rather than pattern: a wool throw, a jute or wool rug, linen cushions. A single statement chair or pendant often provides the focal point.

Briefing a stager. Request pale oak floors and furniture if your floors allow, a light grey or oatmeal sofa, a simple round coffee table, linen curtains, a sheepskin, and plants used sparingly. Ask that the space feel uncluttered with visible floor area.

Japandi

Origins. Japandi is a contemporary hybrid of Japanese and Scandinavian design. The two traditions share an emphasis on simplicity, craftsmanship, natural materials and calm. The Japanese aesthetic concept of wabi-sabi, which finds beauty in imperfection and impermanence, often informs the Japanese side of the blend.

Defining features. Low furniture, muted earthy palettes such as warm greys, beiges, clay and charcoal, a mix of light and dark woods, natural textures like paper, linen, rattan and stone, handmade ceramics, and very restrained decoration.

Furniture planning. Japandi rooms rely on negative space. Choose fewer pieces and leave generous gaps between them. Low platform beds and low sofas emphasize horizontal lines and make ceilings feel higher. Storage should hide clutter, because visible clutter undermines the style faster than almost any other.

Briefing a stager. Ask for a low platform bed or sofa, a slatted wood screen or shelving, paper or linen lighting, a single large ceramic vessel, and a neutral rug with subtle texture. Specify limited accessories. AI staging tools frequently overfill rooms; with Japandi, explicitly ask for minimal decor.

Minimalist

Origins. Minimalism in interiors draws on modernist architecture, including the principle often summarized as “less is more,” and on Japanese spatial traditions. It emphasizes essential forms and the removal of anything unnecessary.

Defining features. Monochrome or very limited palettes, flat or simple surfaces, hidden storage, clean geometry and few objects. Every piece is expected to justify its presence.

Furniture planning. In minimalist rooms, every proportion is exposed, so scale errors are glaring. Measure carefully, choose pieces that fit the room precisely, and align furniture with architectural lines. Minimalism can feel cold if texture is absent; consider tactile materials such as boucle, plaster or natural wood.

Briefing a stager. Request a limited number of pieces, a monochrome or two-tone palette, and no small decorative objects beyond one or two. Ask for an alternative version with added texture so you can judge whether pure minimalism suits you or you prefer a warmer version.

Contemporary and Modern

Clarifying the terms. In design, “modern” often refers to the historical modernist movement of the twentieth century, while “contemporary” refers to whatever is current. In everyday use, people often use them interchangeably to mean clean-lined, current furniture.

Defining features. Contemporary interiors today commonly feature curved and rounded forms, boucle and performance fabrics, warm neutrals, mixed metals, large-format art and statement lighting.

Furniture planning. Curved sofas and round tables soften rooms and improve flow in tight spaces, because rounded corners are easier to walk around. Large art is common; a guideline often used is to hang art so its center sits roughly 57 to 60 inches from the floor, adjusted for furniture beneath it.

Briefing a stager. Ask for a curved or modular sofa, a sculptural coffee table, warm neutral walls, one large artwork and a statement pendant or floor lamp.

A Style-by-Style Guide, Part Two: Warmth, History and Character

Industrial

Origins. Industrial style grew out of the conversion of former factories, warehouses and lofts into homes, a trend widely associated with cities such as New York from the mid-twentieth century onward. Rather than hiding the building’s original structure, these interiors celebrated it.

Defining features. Exposed brick, concrete, steel beams and ductwork; metal and reclaimed wood furniture; leather upholstery; factory-style pendant lights; and a palette of greys, blacks, rust and warm browns.

Furniture planning. Industrial spaces are often large and open, which makes zoning essential. Use large rugs to anchor seating groups and long dining tables to define eating areas. Because hard materials dominate, add softness through leather, wool and textiles to stop the room from feeling cold or echoing.

Briefing a stager. Request a cognac leather sofa, a reclaimed wood coffee table with metal legs, metal-framed shelving, and black metal pendants. If your room has no exposed brick or concrete, be cautious: staging cannot honestly add architectural features, and a room without them may suit a softer “industrial-inspired” approach using furniture alone.

Modern Farmhouse

Origins. Modern farmhouse blends rustic rural traditions with clean contemporary lines. It became especially popular in the United States in the 2010s, helped by home renovation television.

Defining features. White or warm white walls, shiplap or board-and-batten paneling, natural wood, black metal fixtures, slipcovered sofas, farmhouse dining tables, vintage-inspired accessories, and neutral palettes with occasional muted greens or blues.

Furniture planning. Farmhouse rooms tend to center on gathering: a large dining table, a comfortable sofa, generous seating. Allow enough clearance around dining tables; a common guideline is roughly 36 inches between the table edge and a wall or other furniture so chairs can be pulled out, and more where people need to walk behind seated guests.

Briefing a stager. Request a slipcovered or linen sofa, a wood dining table with mixed chairs or a bench, black metal lighting, woven baskets and simple greenery. Ask the stager not to add shiplap or beams unless you plan to install them, because those are architectural changes rather than furniture.

Traditional

Origins. Traditional style draws on eighteenth- and nineteenth-century European design, including English Georgian and French influences. It values symmetry, craftsmanship and established forms.

Defining features. Rolled-arm sofas, wingback chairs, dark polished woods, carved details, patterned fabrics such as damask or florals, layered window treatments, and symmetrical arrangements.

Furniture planning. Symmetry is the organizing principle: pairs of lamps, matching chairs flanking a fireplace, a sofa centered on a focal wall. Traditional furniture is often visually heavy, so balance large pieces across the room and avoid crowding.

Briefing a stager. Ask for a symmetrical layout around the focal point, a rolled-arm sofa, two matching armchairs, a pair of table lamps, a patterned rug and classic framed art.

Transitional

Origins. Transitional style sits between traditional and contemporary. It keeps the comfort and familiarity of traditional forms while simplifying ornament and palette.

Defining features. Neutral palettes, simple silhouettes with subtle classic details, a mix of wood and metal, and restrained pattern. It is one of the most broadly appealing styles, which is why it is widely used in real estate staging.

Furniture planning. Transitional rooms tolerate a wide range of pieces, making them forgiving for people who already own furniture from different eras. Use a consistent palette to tie mixed pieces together.

Briefing a stager. Request a track-arm or simple rolled-arm sofa in a neutral fabric, a wood coffee table with clean lines, a mix of brushed metal and wood accents, and a textured neutral rug.

Bohemian

Origins. Bohemian, or boho, style takes its name from artistic, unconventional lifestyles and draws on global textiles and crafts. Its contemporary form gained popularity alongside the 1960s and 1970s counterculture and has had several revivals since.

Defining features. Layered textiles, patterned rugs, rattan and wicker, floor cushions, macrame, abundant plants, warm earthy colors and collected objects from different places and eras.

Furniture planning. Boho rooms look relaxed but still need structure. Anchor the layout with one solid sofa and a large rug, then layer smaller rugs, poufs and floor cushions. Keep walkways clear, because layered rooms quickly become cluttered.

Briefing a stager. Ask for layered rugs, a rattan chair, a low sofa with patterned cushions, several plants of varying heights, and woven wall hangings. Request a calmer version too, since boho staging can easily tip into chaos.

Coastal

Origins. Coastal style draws on seaside living. It is related to, but distinct from, nautical themes; contemporary coastal design generally avoids literal motifs like anchors in favor of light, airy atmospheres.

Defining features. White and sand tones, soft blues and greens, natural fibers such as jute and seagrass, light woods, linen slipcovers and abundant natural light.

Furniture planning. Coastal rooms emphasize light and views. Orient seating toward windows where possible, keep window treatments light, and avoid heavy dark pieces.

Briefing a stager. Request a white or sand linen sofa, a jute rug, light wood furniture, sheer curtains and a few blue or green accents. Ask that decor stay subtle rather than themed.

Art Deco

Origins. Art Deco takes its name from the 1925 Exposition Internationale des Arts Décoratifs et Industriels Modernes in Paris and flourished in the 1920s and 1930s. It combined luxurious materials with bold geometry.

Defining features. Geometric patterns, symmetry, lacquered and mirrored surfaces, brass and gold accents, velvet upholstery, rich jewel tones, and curved, glamorous furniture forms.

Furniture planning. Art Deco works best when one or two statement pieces carry the look, such as a curved velvet sofa or a mirrored sideboard. Too many glamorous pieces in one room can feel theatrical.

Briefing a stager. Ask for a curved velvet sofa in emerald, sapphire or blush, brass-legged tables, a geometric rug and a statement chandelier. Request a restrained version so you can compare.

Maximalist

Origins. Maximalism is less a historical style than an attitude: a deliberate embrace of color, pattern and abundance, often in reaction to minimalism.

Defining features. Bold colors, mixed patterns, gallery walls, collections on display and layered textures.

Furniture planning. Maximalism still needs a backbone. A consistent color thread, repeated shapes or a unifying material keeps abundance from becoming chaos.

Briefing a stager. Provide a color palette and a few reference images, because “maximalist” without direction produces random results, especially from AI tools.

Blending styles

Most real homes blend styles. Common pairings include Scandinavian with Japanese (Japandi), mid-century with contemporary, farmhouse with industrial, and traditional with modern (transitional). Virtual staging is ideal for testing blends: ask for the same room in each pure style, then in a blended version, and compare.

Room-by-Room Furniture Planning with Virtual Staging

Style tells you what a room should feel like. Planning tells you whether it will actually work. This section walks through the main rooms of a home and explains how to use virtual staging to test layouts, not just looks.

Living rooms

The living room is where most layout decisions happen, and where most mistakes are made.

Start with the purpose. Is this room for watching television, conversation, reading, entertaining or all four? A television-focused room arranges seating facing the screen; a conversation-focused room arranges seating facing itself. Ask your stager for both versions if you are unsure.

Choose a seating layout. Common arrangements include a sofa facing two chairs across a coffee table, an L-shaped sectional anchoring a corner, a pair of facing sofas for symmetry, or a sofa with a chaise in smaller rooms. Each changes how the room flows. A floating layout, with the sofa pulled away from the wall, often makes a room feel more intentional and can improve conversation, though it requires enough space behind the sofa for a walkway or a console table.

Check the conversation distance. Seating that is too far apart makes conversation awkward. Many designers aim to keep facing seats within roughly 8 to 10 feet of each other. In large rooms, create two smaller seating groups rather than stretching one group across the space.

Test the television placement. If the room includes a screen, staging can show how it relates to windows and seating. Glare from windows opposite a screen is a common problem that a staged image, taken at the time of day you usually watch, can reveal.

Use staging to compare sofa sizes. One of the most useful requests you can make is the same room with two or three sofa sizes, for example a compact apartment sofa, a standard three-seater and a sectional. Seeing them side by side, scaled to your measured room, is far more informative than reading dimensions on a product page.

Dining areas

Table shape follows room shape. Rectangular tables suit long rooms, round tables suit square rooms and tight spaces, and oval tables offer a compromise with softer corners. Round tables encourage conversation and make it easier to squeeze in an extra guest.

Allow space per diner. A common guideline is to allow about 24 inches of table width per seated person, more for armchairs. Combine this with the clearance guideline of roughly 36 inches between table edge and walls or furniture.

Hang lighting at the right height. Pendants and chandeliers over dining tables are often hung so their bottom sits around 30 to 36 inches above the tabletop in rooms with standard ceilings. Staging can show whether a fixture’s scale suits the table; a common guideline is that a fixture’s width is roughly half to two-thirds of the table’s width.

Test open-plan zoning. In open plans, ask your stager to show how the dining area relates to the kitchen and living area. A rug under the dining table and a pendant above it are often enough to define the zone.

Bedrooms

Bed placement first. The bed is the largest piece and usually goes on the wall opposite or adjacent to the entrance, often with the headboard against a solid wall rather than under a window. Allow walking space on both sides of the bed where possible; around 24 to 30 inches is a common minimum.

Check bed size against room size. A king bed can dominate a small bedroom. Staging the same room with a queen and a king, scaled to your measurements, shows the trade-off between sleeping space and floor space clearly.

Nightstands and lighting. Nightstands are typically chosen to be roughly level with the top of the mattress. Wall-mounted sconces can free surface space in small rooms. Ask your stager to show both table lamps and sconces.

Storage. Dressers, wardrobes and benches compete for space. Staging can test whether a dresser fits opposite the bed without blocking a closet door or window.

Home offices

Light and orientation. Placing a desk perpendicular to a window often provides good daylight without glare on the screen or the user’s face in silhouette on video calls. Staging can compare a desk facing the wall, facing the window and facing into the room.

Dual-purpose rooms. Many home offices double as guest rooms. Ask for staging that shows a sleeper sofa or daybed alongside the desk, and confirm that both functions fit without blocking circulation.

Video-call backgrounds. A small but practical use of staging is designing what appears behind you on calls: shelving, art and plants arranged deliberately rather than by accident.

Small spaces and studios

Multi-functional furniture. Extendable tables, storage beds, nesting tables and wall-mounted desks are common tools for small spaces. Staging can show how a studio works in two modes, for example day and night.

Visual tricks. Leggy furniture, mirrors, consistent palettes and vertical storage make small rooms feel larger. Curtains hung higher and wider than the window frame can make windows and ceilings appear larger.

Zoning without walls. Bookcases, rugs and the back of a sofa can separate sleeping, living and working zones in a studio. Staging shows whether the zones feel distinct or cramped.

Outdoor spaces

Balconies, patios and terraces are often overlooked. Staging outdoor furniture is generally straightforward and honest, as long as the image does not alter the view, landscaping or building condition. Measure carefully, because outdoor furniture is often bulkier than it looks.

Working with Virtual Stagers

Whether you use an AI tool yourself or hire a virtual staging service, the quality of what you get depends heavily on what you provide. This section explains how to prepare, brief and review staging when your goal is design planning rather than a property listing.

Choosing between AI tools and human stagers

Use AI tools for exploration. When you want to see your living room in eight different styles before deciding on a direction, AI tools are ideal. They are fast, inexpensive and let you regenerate as often as you like. Treat the results as mood boards in your own room, not as precise plans.

Use human or hybrid stagers for decisions. When you are choosing between specific pieces, need accurate scale or want to show a client a polished proposal, a human-reviewed service is usually worth the extra cost. Human stagers can work from your measurements, place furniture at true scale, match shadows and lighting carefully, and follow precise instructions.

Watch for AI alterations. Generative tools sometimes change fixed features while adding furniture: a window grows, a radiator vanishes, flooring changes color or a doorway moves. For planning, this is more than an aesthetic issue, because a layout that only works with a missing radiator does not work at all. Always compare the staged image with the original photo.

Preparing your photos

Good staging begins with good photographs.

  • Shoot each room from a corner, showing two walls, to capture depth and geometry.
  • Hold the camera level, ideally on a tripod, around chest height.
  • Show as much floor as possible, because furniture needs a visible floor to sit on.
  • Photograph in natural daylight with lights switched on, avoiding strong mixed color temperatures.
  • Remove clutter, or ask for virtual decluttering if furniture cannot be moved.
  • Take several angles of each room so you can stage the one that best shows the layout.

Avoid extreme wide-angle settings on phones, which stretch the edges of the frame and make scale hard to judge.

Writing a good brief

A strong brief is specific without being rigid. For each room, include:

  1. Purpose. How the room will be used and by whom: a family living room, a quiet reading room, a guest room that doubles as an office.
  2. Measurements. Room dimensions, ceiling height, and the size and position of windows, doors, radiators and outlets.
  3. Style direction. The style or blend you want to test, plus two or three reference images that capture the mood.
  4. Fixed items. Any furniture you already own and plan to keep, with dimensions and photos.
  5. Must-haves and must-nots. For example: seating for six, a desk for two monitors, no glass tables because of young children, no rugs because of a pet.
  6. Budget tier. Whether pieces should look high-end, mid-range or budget, so the staging reflects what you can realistically buy.
  7. Variations. How many versions you want, for example the same layout in two styles, or two layouts in the same style.

A simple brief for a living room might read: Family living room, 14 by 18 feet, 8-foot ceiling. Fireplace centered on the long wall is the focal point. Test a Scandinavian layout with a three-seater sofa facing the fireplace and two armchairs, and a second version with an L-shaped sectional. Keep the existing walnut sideboard on the window wall. Warm neutral palette, pale oak, wool textures. No glass tables. Leave a clear path from the hallway door to the patio door.

Reviewing staged images

When results arrive, review them like a designer, not a buyer.

  • Scale. Compare furniture against doors, windows and outlets. Does the sofa look plausible for the dimensions you supplied?
  • Circulation. Can you trace a comfortable walking path from each door to the main areas?
  • Focal point. Is the furniture oriented the way you would actually use the room?
  • Light. Does the furniture’s lighting match the room’s light direction and color?
  • Fixed features. Has anything permanent been altered, removed or invented?
  • Livability. Is there somewhere to put a drink, a bag, a book? Overstyled images often omit the practical details of daily life.

Request revisions with specific notes, such as “move the sofa 12 inches away from the radiator” or “replace the round coffee table with a rectangular one around 48 by 24 inches,” rather than general comments like “make it cozier.”

Turning staging into a shopping list

The most valuable step is translating staged images into real purchases. Ask human stagers whether they can identify the dimensions of the pieces they used, or source similar products. With AI tools, use the staged image as a visual target and search for pieces that match the shape, proportion and material.

Before buying, return to your measurements. Check that each real piece fits the space shown in the staging, including doorways and stairwells it must pass through on delivery. Many furniture returns happen not because a sofa looks wrong, but because it cannot get through the door.

Honesty and disclosure

If you are a designer showing staged images to clients, or a homeowner sharing them online, be clear that they are visualizations. If staged images are used to sell or rent a property, many jurisdictions and listing services require them to be labeled. California, for example, now requires real estate licensees to disclose digitally altered listing images and provide access to the originals. Even where it is not required, labeling staged images protects trust.

A Worked Example: One Living Room, Three Directions

To show how these ideas fit together, here is a hypothetical planning exercise. The room and decisions are illustrative, not a real project.

Imagine a living room measuring 13 by 16 feet with an 8-foot ceiling. A large window sits on one long wall, the entrance door is in a corner, and a radiator sits beneath the window. The owners plan to keep a walnut sideboard and want seating for four, a place to read, and a television that does not dominate the room.

Step one: measure and photograph. The owners measure every wall, note the window’s width and sill height, the radiator’s length, and the door swing. They photograph the room from two corners in daylight with the lights on.

Step two: explore with AI. Using an AI staging tool, they generate the room in six styles: Scandinavian, Japandi, mid-century modern, modern farmhouse, bohemian and Art Deco. They are drawn to the mid-century and Scandinavian versions and rule out the others quickly. Two of the AI images moved the radiator and one widened the window, so they treat those images only as mood references.

Step three: brief a human stager. They send the measurements, the photo, the sideboard’s dimensions and a short brief asking for two layouts in a blended mid-century and Scandinavian style. Layout A places a three-seater sofa facing the window wall with the television above the sideboard. Layout B floats a compact sofa in the middle of the room facing a pair of armchairs, with the television on a narrow console and a reading chair in the corner by the window.

Step four: review critically. In layout A, the sofa sits close to the entrance path, leaving roughly 28 inches to walk past, tighter than they’d like. In layout B, the floating sofa preserves a clear path from the door, and the reading corner gets the best light. However, the armchairs make the television viewing angle awkward for two seats.

Step five: refine. They ask for a revision of layout B with a slightly larger sofa, one armchair replaced by a swivel chair that can turn toward the screen, and a round coffee table to soften circulation. The revised image works: clear paths, a strong reading corner, comfortable viewing, and the sideboard still anchoring the window wall.

Step six: shop and verify. The owners list the dimensions of each staged piece, search for real products within a few inches of those sizes, and check each against their measurements and the width of their front door and hallway.

The exercise costs a few hours and a modest staging fee. It replaces what could easily have been a costly mistake: buying a large sofa for layout A and discovering only after delivery that the room felt cramped at the entrance.

What this example shows is that the value of staging rarely lies in a single beautiful image. It lies in the comparison between versions, and in the conversation those versions provoke. Each round of staging answered a specific question: which style, which layout, which pieces. By the time the owners spent real money, most of the uncertainty had already been removed, and the remaining decisions were about details rather than direction. That is the most practical way to think about virtual staging in interior design: as a sequence of inexpensive experiments.

Common Mistakes When Planning with Virtual Staging

Virtual staging is a powerful planning tool, but it can also mislead. These are the mistakes I see most often, and how to avoid them.

Trusting the image over the tape measure. A staged image is a picture, not a floor plan. Even good staging can be off by several inches, and AI staging can be off by much more. Always confirm decisions against measured dimensions.

Falling for overstyled rooms. Staged rooms often look perfect because they contain nothing of daily life: no chargers, school bags, laundry baskets or shoes. Plan storage for the things you actually own, and ask your stager to include a few realistic items.

Ignoring the light at different times. A room photographed in bright afternoon light can feel very different on a winter evening. If you can, photograph rooms at the times you use them most, and ask for staging that reflects artificial lighting in the evening.

Testing only one style. The value of virtual staging comes from comparison. Seeing a room in three or four styles often reveals a preference you didn’t know you had, or shows that a style you loved online doesn’t suit your actual space.

Forgetting about existing furniture. Most people don’t start from an empty room. Include the pieces you plan to keep in every staged version, so you see how new purchases will work with them.

Overlooking delivery and installation. A sofa that fits the room may not fit the stairwell. A heavy mirror may need wall reinforcement. A pendant may need an electrician. Staging shows the outcome, not the path to get there.

Letting the tool alter the room. If staging quietly removes a radiator, changes the flooring or enlarges a window, the plan it shows is fiction. Compare every result with the original photograph.

Copying a style too literally. Period-perfect rooms can feel like museum displays. Most livable interiors borrow the essence of a style, such as its palette, materials and shapes, rather than reproducing every element.

Conclusion: Design First, Buy Second

Interior design has always involved imagining a room that does not exist yet. Virtual staging makes that imagining visible, inside a photograph of your real space, and that changes how decisions get made. Instead of committing to a sofa based on a showroom visit and a hopeful guess, you can see it in your own light, against your own walls, next to the sideboard you already own.

Used well, staging is not a shortcut around good design principles. It is a way to apply them more carefully. Scale, circulation, focal points, zoning, rug sizing, lighting layers and visual balance still determine whether a room works. Staging simply lets you test those principles before money changes hands.

The approach I recommend is simple. Measure carefully. Use AI staging to explore styles broadly and cheaply. Narrow down to one or two directions. Use human or hybrid staging, briefed with precise measurements and constraints, to test specific layouts and pieces. Review every image critically, compare it with the original photo, and turn the result into a shopping list checked against your tape measure.

Design first, buy second. The room you can’t yet see becomes the room you can plan with confidence.

Frequently Asked Questions

Can virtual staging replace an interior designer?

No. Staging visualizes ideas; it does not generate good ones on its own, solve complex spatial problems or manage a project. Many designers now use virtual staging as part of their process, but the design judgment still comes from people.

Is AI staging accurate enough for furniture planning?

It is accurate enough for exploring styles and general layouts. It is often not accurate enough for precise decisions about specific pieces, because AI tools may distort scale or alter the room. For final decisions, check against measurements or use a human-reviewed service.

How many styles should I test?

Three or four is usually enough to reveal a clear preference. Include at least one style you think you won’t like; it often clarifies what you do want.

Can I stage a room that still has furniture in it?

Yes, through virtual decluttering, which digitally removes existing furniture before restaging. It is more error-prone than staging an empty room, so review results carefully, especially around floors and walls where furniture was removed.

Can virtual staging show paint colors or new flooring?

Many services offer this as virtual renovation. It is useful for planning, but treat it as a separate, more speculative step. Screen colors differ from real paint, so always test physical samples on your walls.

Does virtual staging work for rentals?

Yes. Renters often can’t change walls or floors, which makes furniture and textiles the main design tools. Staging helps renters plan within those limits and avoid buying pieces that won’t fit the next apartment either.

What should I bring to a virtual stager?

Photos of each room taken from a corner, room measurements including windows and doors, a list of furniture you are keeping, your style references, your budget tier and any practical constraints such as pets, children or accessibility needs.

Glossary

Accent lighting: Lighting used to highlight art, architecture or objects.

Ambient lighting: General illumination for a room.

Circulation: The paths people use to move through a space.

Focal point: The feature a room is arranged around, such as a fireplace, window or artwork.

Hygge: A Danish concept describing a cozy, contented atmosphere, often associated with Scandinavian interiors.

Japandi: A hybrid of Japanese and Scandinavian design emphasizing simplicity, natural materials and calm.

Negative space: Intentionally empty space that gives a room balance and breathing room.

Proportion: The size relationship between pieces of furniture.

Scale: The size of furniture relative to the room.

Task lighting: Focused light for specific activities such as reading or cooking.

Virtual decluttering: Digitally removing existing furniture or clutter from a photograph.

Virtual renovation: Digitally changing fixed features such as paint, flooring or cabinetry.

Virtual staging: Digitally adding furniture and decor to a photograph of a real space.

Visual weight: How heavy a piece of furniture appears, regardless of its physical weight.

Wabi-sabi: A Japanese aesthetic concept that finds beauty in imperfection and impermanence.

Zoning: Dividing an open space into distinct functional areas using furniture, rugs and lighting.
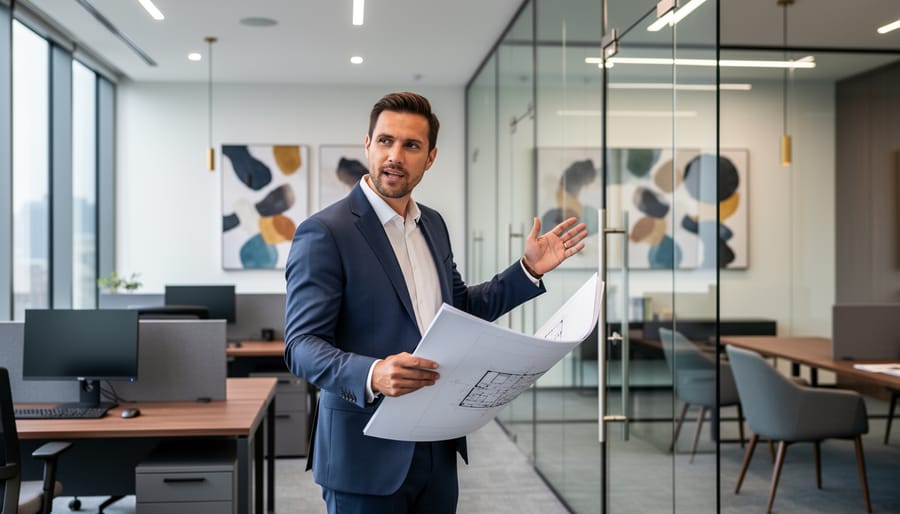
A corporate real estate professional reviewing an architectural plan in a modern office with glass conference rooms and contemporary design elements.

Corporate Real Estate Jobs That Blend Business Strategy with Beautiful Spaces

Corporate real estate jobs sit at the intersection of property strategy, financial analysis, and business operations, offering professionals the opportunity to manage portfolios, negotiate leases, and shape workplace environments for organizations ranging from Fortune 500 companies to design-driven startups. Unlike traditional commercial brokerage, these positions function within a company’s internal structure, where real estate decisions directly support brand identity, employee experience, and operational efficiency. For those drawn to the styling and design sectors, this career path presents a compelling hybrid: you’re not just securing square footage, you’re partnering with architects, interior designers, and facilities teams to create spaces that reflect corporate culture and aesthetic vision.

The demand for corporate real estate professionals has shifted considerably in recent years. Companies now expect their real estate teams to understand spatial planning, workplace trends, and how physical environments influence productivity and brand perception. This evolution has opened doors for candidates with backgrounds in design, architecture, or creative industries who bring fresh perspectives to traditionally finance-heavy departments. Portfolio managers at hospitality brands collaborate with stylists on flagship properties. Workplace strategists at tech firms work alongside interior designers to reimagine office layouts. Real estate coordinators in retail oversee store aesthetics as much as lease terms.

What makes these roles particularly attractive is the global scope. Multinational corporations require professionals who can navigate diverse markets, cultural preferences, and design sensibilities across regions. The work combines analytical rigor with creative problem-solving, making it ideal for those who want to influence how spaces look and feel while building a strategic business career.

Understanding Corporate Real Estate Roles in the Styling Industry

Corporate real estate team members discussing styling materials and plans in a modern staged office.
A corporate team reviews plans for a newly styled commercial space, blending strategy with design execution.

Traditional corporate real estate roles have undergone a significant transformation as the property industry recognizes staging and styling as essential business tools rather than optional extras. Where corporate real estate positions once focused purely on transactions, market analysis, and client acquisition, today’s roles increasingly demand fluency in how design impacts property value and buyer psychology.

This evolution reflects a fundamental shift in how properties are marketed and sold. Real estate professionals working within styling companies now operate at the intersection of two disciplines, requiring them to speak both languages fluently. They must understand property development cycles and market dynamics while also grasping how a well-staged dining room influences purchase decisions or how color psychology affects buyer perception.

Companies like Loand Styles exemplify this hybrid approach. Corporate team members don’t just sell styling services, they function as strategic advisors who help real estate agents and developers understand the return on investment that professional staging delivers. A business development manager might analyze a property developer’s portfolio, identify presentation challenges, and propose targeted styling solutions that address specific market positioning goals.

These positions demand a unique mindset. You’re not simply a real estate professional who appreciates good design, nor are you a designer dabbling in business. Instead, you become a translator between two worlds, helping property professionals understand design impact while ensuring creative teams appreciate commercial realities like budget constraints and market timing.

The most successful candidates bring genuine curiosity about both domains. They can discuss absorption rates and staging turnaround times in the same conversation, recognizing that beautiful spaces and solid business strategy aren’t competing priorities, they’re complementary forces that drive results in today’s competitive property market.

High-Demand Positions at the Intersection of Corporate Real Estate and Styling

Corporate Business Development Managers

Corporate Business Development Managers serve as the critical bridge between styling service providers and the property industry’s decision-makers. These professionals identify and cultivate relationships with property developers planning new residential projects, real estate agencies seeking competitive advantages, and commercial clients managing portfolios that require transformation.

The role demands fluency in two distinct languages: the metrics-driven world of real estate transactions and the aesthetic vocabulary of interior design. You’ll need to articulate how strategic styling increases property values and accelerates sales cycles while understanding market trends, competitive positioning, and development timelines. A typical week might include presenting ROI projections to a developer, touring a staged property with potential agency partners, and negotiating service agreements that align with construction schedules.

Success requires exceptional relationship management across cultures and markets. You’re not selling products; you’re proposing partnerships that enhance how properties are perceived and sold. The compensation reflects this complexity, typically combining base salary with performance incentives tied to new contracts secured and long-term client retention. For those who understand both balance sheets and colour palettes, these positions offer substantial earning potential and genuine influence over how properties enter the market.

Property Marketing Specialists

Staged modern commercial room with neutral furnishings and warm sunlight through large windows.
An upscale, design-forward room demonstrates how styling elevates the presentation of commercial or development spaces.

Property Marketing Specialists bridge the gap between traditional real estate promotion and the visual storytelling that transforms listings into must-see opportunities. These professionals understand that compelling property presentations directly influence market performance, crafting campaigns that highlight a space’s potential through strategic staging insights. They coordinate with photographers, create digital assets, and develop presentation materials that speak to both agents and end buyers.

A significant aspect of this role involves managing virtual styling service implementations, especially for international properties or pre-construction developments where physical staging isn’t feasible. These specialists analyze target demographics, recommend styling approaches that resonate with specific buyer profiles, and translate design decisions into marketing narratives that demonstrate value. They’re the ones explaining to developers why a £15,000 staging investment helps properties sell faster and command premium prices.

Successful candidates combine copywriting ability, visual literacy, and data analysis skills, tracking which styled presentations generate the most viewings and adjusting strategies accordingly. They work closely with both the creative team and sales divisions, ensuring brand consistency across markets while adapting campaigns to regional preferences.

Client Relations and Account Managers

Client Relations and Account Managers serve as the crucial bridge between styling companies and their real estate partners, maintaining ongoing relationships that drive repeat business. These professionals manage portfolios of agents, agencies, and developers, understanding each client’s unique market positioning and property types. You’ll spend your days coordinating project timelines, ensuring client satisfaction, and identifying opportunities to expand services within existing accounts.

Success requires genuine bilingual fluency: speaking confidently about staging ROI and market days with agents while translating those business concerns into actionable design briefs for styling teams. You’re constantly balancing client expectations with project realities, negotiating timelines when properties need rapid turnaround, and managing budget conversations that respect both profitability and client constraints.

The role demands strong organizational skills, you’ll juggle multiple projects simultaneously, anticipate seasonal demand fluctuations, and maintain detailed records of client preferences and past projects. Relationship depth matters more than volume; excellent account managers develop trusted advisor status where agents consult them before listings even hit the market, creating pipeline visibility that benefits everyone involved.

Project Coordinators for Real Estate Clients

Project coordinators serve as the operational backbone for styling companies working with real estate clients, managing the intricate logistics that transform empty properties into market-ready showcases. These professionals orchestrate furniture deliveries, coordinate with staging teams across multiple properties, and ensure each project meets deadlines that align with listing schedules and open house dates.

The role demands exceptional organizational skills and the ability to juggle competing priorities. A coordinator might simultaneously manage installations for a developer’s new apartment complex, schedule photography for an agent’s luxury listing, and arrange furniture returns from a recently sold property. They maintain detailed inventory systems, track styling assets across locations, and solve problems in real-time when deliveries run late or last-minute client requests arise.

Communication forms the core of this position, liaising between designers, warehouse teams, real estate agents, and property managers to keep everyone informed. Coordinators also handle budget tracking, invoice processing, and timeline management, ensuring projects stay profitable while meeting client expectations. For detail-oriented professionals who thrive on behind-the-scenes orchestration rather than client-facing sales or design work, project coordination offers steady employment with clear career progression toward operations management roles.

Essential Skills for Corporate Real Estate Styling Careers

Business and Real Estate Expertise

Professionals entering corporate real estate styling roles need a solid foundation in property markets and business operations. Commercial awareness means understanding how economic shifts, interest rate changes, and demographic trends influence both property values and styling demand. When developers face tighter margins, your ability to demonstrate return on investment for staging services becomes critical to closing contracts.

Market analysis skills extend beyond reading property reports. You’ll track which neighborhoods are appreciating, which property types attract multiple offers, and how quickly styled homes sell compared to unstaged counterparts. This data becomes your most persuasive tool when pitching to skeptical real estate agents or budget-conscious developers.

Client acquisition in this field differs from traditional sales. You’re building relationships with decision-makers who control multiple properties rather than individual homeowners. Understanding their quarterly targets, inventory turnover rates, and competitive pressures allows you to position styling as a strategic advantage, not an aesthetic luxury.

Familiarity with property development cycles proves essential when coordinating large-scale projects. Knowing when developments reach pre-sale phases or when rental properties need refreshing helps you anticipate client needs. You’ll also need to articulate how design choices like minimalist home decor accelerate transactions by appealing to contemporary buyers’ preferences while keeping staging costs manageable.

Design and Styling Fluency

You don’t need a design degree to succeed in these roles, but you do need enough fluency to speak confidently with stylists and understand why certain choices matter. When a designer proposes swapping out existing furniture or adding specific decor accessories you should grasp the rationale, not just nod along. Recognizing how neutral palettes broaden buyer appeal, why lighting transforms perceived space, or how staging creates emotional connection helps you explain these concepts to skeptical clients who see only added cost.

The most valuable skill is translating design decisions into business outcomes. Can you articulate to a developer how a $3,000 staging investment might yield a $15,000 faster sale? Can you explain to an agent why virtual staging works for some listings but physical transformation better serves high-end properties? This isn’t about executing the design yourself; it’s about understanding staging’s measurable impact on time-on-market, sale price, and buyer perception. You become the bridge between creative vision and commercial reality, ensuring both designers and business clients feel heard and their priorities addressed.

Career Pathways and Professional Development

Close-up of hands adjusting pillows and blankets on a staged sofa in a design studio.
Detail-focused styling work shows the precision behind creating spaces that support real estate outcomes.

Most professionals enter corporate real estate styling through one of three doors: a real estate background seeking creative application, a design education wanting business structure, or a business degree attracted to the creative industries. What matters most isn’t which door you choose but how you build the bridge between disciplines once inside.

The typical entry point is a business development associate or junior account coordinator role, where you’ll shadow experienced managers while developing your dual fluency. Universities don’t typically offer “corporate real estate styling” degrees, but business administration, marketing, property management, and interior design programs all provide relevant foundations. What distinguishes successful candidates is demonstrated interest in both sides, perhaps real estate internships paired with design coursework, or business studies complemented by staging volunteer work.

Professional certifications strengthen your profile considerably. While no single credential covers the hybrid nature of these roles, combinations prove powerful: a real estate license paired with staging certification, or project management credentials alongside design software proficiency. Many international styling companies value language skills and cross-cultural competency as much as formal qualifications, particularly for roles managing diverse property markets.

Career progression typically follows this trajectory:

  1. Entry-level coordinator (1-2 years): Learn client communication, project logistics, and how staging transforms property presentations
  2. Business development associate (2-3 years): Begin managing smaller accounts, supporting proposals, and understanding commercial relationships
  3. Senior account manager (3-5 years): Own client portfolios, negotiate contracts, and translate between design teams and corporate clients
  4. Regional director or VP level (5+ years): Develop market strategies, build partnerships with major developers, and potentially lead international expansion

Growth accelerates when you actively cultivate both competencies rather than leaning solely on your comfort zone. Attend property development conferences and design trade shows. Shadow colleagues on the opposite side of the business-creative divide. The most valuable professionals speak both languages fluently and can translate between them seamlessly, whether explaining ROI to a designer or aesthetic impact to a CFO.

The International Advantage: Remote and Global Opportunities

Corporate real estate styling careers in 2026 offer unprecedented geographic flexibility that sets them apart from traditional property roles. The digital transformation of both real estate and interior design has created positions where professionals coordinate projects across multiple countries without relocating, opening doors for talent regardless of location.

Remote positions typically involve managing client relationships, coordinating with local styling teams, and overseeing project execution through digital platforms. Video consultations replace many in-person meetings, while project management software tracks everything from initial client contact through final property presentation. A business development manager might work with developers in Dubai, Singapore, and London simultaneously, coordinating time zones and cultural preferences while maintaining consistent brand standards.

Technology bridges the distance gap effectively. Virtual staging software allows teams to preview designs before physical implementation. Cloud-based collaboration tools enable real-time feedback between corporate clients, styling teams, and photographers. Quality assurance happens through detailed photo documentation and video walkthroughs rather than physical site visits for every project phase.

Companies maintain standards across continents through rigorous training programs, comprehensive style guides, and established vendor networks in each market. Regional teams execute the hands-on work while corporate coordinators ensure consistency with brand vision and client expectations. This structure creates career opportunities for those who excel at orchestration and communication rather than solely hands-on design work.

The international scope also means exposure to diverse property markets and design preferences. Professionals develop cultural fluency and market awareness that accelerates career growth. Many companies value multilingual skills and understanding of regional real estate practices, rewarding those who bring cross-cultural expertise to client relationships and team coordination.

Compensation, Budget Management, and Client Diversity

Corporate real estate styling positions typically offer base salaries ranging from £35,000 to £75,000 annually depending on experience level and responsibilities, with senior business development and account management roles commanding higher ranges. Many positions include commission structures tied to project acquisition or client retention, potentially adding 20-40% to total compensation for high performers who successfully close styling contracts with property developers and agencies.

The financial complexity of these roles extends beyond personal earnings to sophisticated budget management across vastly different client types. A corporate business development manager might negotiate a £150,000 staging package for a luxury development one week, then coordinate a modest £3,000 refresh for an individual homeowner the next. This diversity requires genuine fluency in budget optimization, understanding where premium materials create measurable value and where strategic selections deliver impact without unnecessary expense.

Note: Success in these roles means delivering exceptional results whether working with a developer’s substantial budget or helping a homeowner maximize limited resources through smart prioritization.

Market awareness proves essential, as economic factors like how interest rates impact property sales cycles directly influence client budgets and project timelines. Corporate real estate professionals in styling must adapt their approach across client segments, presenting ROI-focused proposals to commercial developers emphasizing faster sales and higher premiums, while offering individual sellers practical solutions that enhance appeal without overinvestment. This financial versatility, combined with the ability to maintain quality standards regardless of budget constraints, distinguishes successful professionals in these hybrid positions.

Corporate real estate jobs within the styling industry represent a rare convergence of strategic business thinking and creative transformation. These positions offer professionals the chance to shape how properties are presented and perceived while building meaningful partnerships across the real estate ecosystem. Unlike traditional corporate roles confined to spreadsheets and boardrooms, or pure design positions focused solely on aesthetics, these hybrid careers demand both analytical rigor and an appreciation for how beautiful spaces influence human decisions.

The professionals who thrive in these roles understand property markets, communicate fluently with developers and agents, and recognize how thoughtful staging translates directly to business outcomes. They navigate budgets, negotiate contracts, and coordinate international teams while maintaining an eye for design excellence. For those energized by variety, collaboration, and the tangible results of well-executed projects, corporate real estate positions in styling companies like Loand Styles offer a compelling alternative to conventional career paths.

As the industry continues evolving in 2026, the demand for individuals who can bridge business strategy and spatial design will only intensify, making now an opportune moment to explore these distinctive professional opportunities.

“Person holding house keys and a mortgage statement folder in a bright living room, representing how interest rates and home prices affect monthly affordability.”

How Much Does Housing Affordability and Interest Rates Impact Your Mortgage Payment? (2026)

Your monthly mortgage payment on a $500,000 home at 2.25% (the Bank of Canada’s current policy rate as of September 2, 2026) sits around $1,950 over 25 years. Drop the price to $450,000 and you’ll pay roughly $1,755. Raise the rate to 3.25% on that same $500,000 property, and the payment climbs to $2,430. The question homeowners and investors wrestle with right now is which variable deserves more attention when timing a purchase: the headline price tag or the borrowing cost.

Key Takeaway: A one-percentage-point rate increase can raise your payment as much as a $50,000 jump in purchase price. Understanding how both levers affect your true carrying cost allows you to evaluate market entry points strategically rather than emotionally.

Both factors shape affordability, but they interact in ways that aren’t immediately obvious. A lower purchase price with a higher rate might cost you more monthly than a pricier home financed at a bargain rate. Over the life of the loan, however, you’ll pay interest on a smaller principal, and refinancing becomes an option when rates drop. Conversely, locking in a low rate on an inflated home price means servicing a larger debt even if borrowing conditions improve later.

The Bank of Canada has held its overnight rate steady at 2.25% since April 2025, signaling cautious optimism as Canada’s economy shows signs of improvement. Rate announcements follow a predictable schedule throughout the year, giving buyers a clear window to model scenarios and make informed decisions. Yet purchase price remains the wild card, driven by inventory levels, location dynamics, and buyer sentiment that can shift faster than central bank policy.

This article walks through the mechanics of how each variable influences your payment, breaks down the total cost of ownership under different scenarios, and offers frameworks for deciding whether to wait for better rates or act on a compelling property at current borrowing costs. For those preparing a home for sale, we’ll also explore how strategic staging can maximize your sale price regardless of rate environment.

The True Cost of Homeownership: Breaking Down Your Monthly Mortgage Payment

A couple holding house keys while considering a calculator on a counter in a bright living room
A homebuyer pair considers their next steps with keys in hand, reflecting how affordability and interest-rate pressures shape daily decisions.

Your monthly mortgage payment tells only part of the homeownership cost story. While most buyers focus on the principal and interest figure lenders quote, the true financial commitment includes several additional components that can add 30-40% to your base payment. Understanding this complete picture matters because a home priced at $500,000 with a 3% interest rate might cost less per month than a $450,000 home at 5%, but only when you account for all expenses, not just the mortgage itself.

The principal and interest portion represents your loan repayment. Principal reduces your debt with each payment, while interest compensates the lender for borrowing risk. These two elements respond differently to market conditions: your principal depends entirely on purchase price and down payment, whereas interest reflects both the amount borrowed and the current rate environment. With the Bank of Canada holding its policy rate at 2.25% through September 2026, mortgage rates have stabilized, but even small rate shifts dramatically alter the interest portion of your payment.

Beyond the mortgage, property taxes claim a significant share of monthly costs. These vary by municipality and property value, typically ranging from 0.5% to 2.5% of your home’s assessed value annually. A $600,000 home in a jurisdiction with 1% annual tax pays $500 monthly just for property taxes, money that never builds equity.

Home insurance protects your investment but adds another $100-300 monthly depending on coverage, location, and property characteristics. Lenders require this protection, and it’s non-negotiable. If your down payment falls below 20%, mortgage default insurance becomes mandatory in Canada, potentially adding another $150-400 to monthly obligations.

Maintenance and repairs demand ongoing funding that many new homeowners underestimate. Financial planners recommend budgeting 1% of your home’s value annually for upkeep. That’s $417 monthly on a $500,000 property, covering everything from furnace repairs to roof replacement.

Home Price Interest Rate Principal + Interest Property Tax + Insurance + Maintenance Total Monthly Cost
$450,000 5.0% $2,172 $1,125 $3,297
$500,000 3.0% $1,896 $1,250 $3,146
$500,000 5.0% $2,413 $1,250 $3,663

These scenarios assume a 20% down payment and 25-year amortization. The difference between the first two rows demonstrates why both variables matter: the higher-priced home with a lower rate costs less monthly than the cheaper home at a higher rate. The comparison between rows two and three shows how a two-percentage-point rate increase on the same home price adds $517 monthly, more than many borrowers budget for total maintenance costs.

The mathematical relationship works multiplicatively, not additively. Your payment doesn’t simply increase by the rate percentage; it compounds based on the total amount financed over the full amortization period. A $400,000 mortgage at 3% costs roughly $1,517 monthly in principal and interest, but the same amount at 5% jumps to $1,931, a 27% increase for a two-point rate change. This explains why lenders qualify you at higher stress-test rates: they’re ensuring you can handle payment increases if rates rise during your mortgage term.

Mortgage planning items with a coin jar and notebook on a table, photographed with soft studio lighting
This scene symbolizes the real-world mix of costs that make up monthly homeownership, like payments, savings, and planning.

How Interest Rate Changes Affect Your Purchasing Power

Understanding the Bank of Canada’s Rate Cycle

Low-angle exterior photo of a central banking building with blurred city activity in the background
A neutral view of the central banking environment represents how policy decisions can ripple into mortgage rates for borrowers.

The Bank of Canada adjusts its target for the overnight rate on eight fixed announcement dates each year, creating a predictable calendar that shapes borrowing costs across the country. These scheduled decisions, falling roughly every six to eight weeks, determine the policy interest rate that influences what Canadians pay on mortgages, lines of credit, and other variable-rate debt. The central bank held the rate steady at 2.25% through September 2, 2026, maintaining that level since April 2025 as policymakers balanced economic growth against inflation control.

Understanding this cycle matters because each announcement ripples through the lending market within days. When the Bank signals a potential shift in direction, lenders adjust their rates before the formal decision even arrives. The overnight rate target sets the floor for what financial institutions charge each other for short-term loans, which directly affects the prime rate that determines your mortgage rates in 2026 and beyond.

Canada’s economy has shown recent weakness but demonstrates signs of improvement heading into late 2026, with growth expected to pick up and inflation projected to remain within the Bank’s target range. This economic context drives monetary policy decisions, the central bank lowers rates to stimulate activity during slowdowns and raises them to cool overheated markets. Four of the eight annual announcements coincide with the Monetary Policy Report, providing detailed economic forecasts that help borrowers anticipate future rate movements and time major purchase decisions accordingly.

From Policy Rate to Your Mortgage Rate

The Bank of Canada’s policy rate is 2.25% as of September 2026, but that figure won’t appear on your mortgage application. Instead, lenders add a spread to determine the rates they quote you, typically 1.5 to 2.5 percentage points above the overnight target for variable-rate mortgages. So while the central bank holds its benchmark steady, your actual variable rate likely sits between 3.75% and 4.75%, depending on your lender and credit profile.

Fixed-rate mortgages follow a different path. They track Government of Canada bond yields rather than the overnight rate directly, which means fixed rates can move independently of central bank decisions. A five-year fixed mortgage might price 1.5 to 2 percentage points above the corresponding bond yield. In periods when markets anticipate future rate cuts, fixed rates sometimes drop even while the policy rate holds steady, or rise when investors expect tightening ahead.

The spread between what the Bank charges financial institutions and what you pay as a borrower reflects lender costs, risk assessment, and profit margins. Borrowers with stronger credit scores, larger down payments, and stable employment secure tighter spreads. Those with weaker profiles face wider gaps between the policy rate and their quoted terms. Your mortgage broker can clarify which rate type suits your situation best, but understanding this layered pricing structure helps you evaluate offers intelligently rather than focusing solely on headline central bank announcements.

Home Price Variables: What Drives Property Costs in Your Market

While interest rates dominate headlines and shape borrowing costs, home prices themselves respond to a distinct set of variables, many of which buyers, sellers, and their advisors can directly influence. Understanding these drivers matters because strategic decisions about property selection, timing, and presentation can offset affordability challenges created by rate environments beyond your control.

Location remains the single most powerful price determinant. Properties in established neighbourhoods with strong school districts, convenient transit access, and desirable amenities command premiums that dwarf the impact of modest rate fluctuations. A home in a sought-after area might sell for 40% more than a comparable property fifteen minutes away, a gap that persists regardless of whether mortgage rates sit at 2.25% or climb higher. For those managing first-time buyer costs this means choosing location strategically can create long-term value appreciation that outpaces temporary rate advantages.

Market inventory levels create immediate price pressure. When supply tightens and available listings drop below typical seasonal norms, competition intensifies and drives prices upward independent of interest rate movements. Conversely, markets flooded with inventory see prices soften as sellers compete for fewer qualified buyers. These supply-demand dynamics shift neighbourhood by neighbourhood, creating opportunities for informed buyers who track local listings rather than relying solely on national trends.

Property condition and presentation exert surprising influence on final sale prices. Two identical homes on the same street can achieve dramatically different outcomes based on how they’re positioned in the market:

  • Professional staging and styling can increase sale prices by 5-15% while reducing time on market
  • Modern, neutral interiors appeal to broader buyer pools and justify premium pricing
  • Well-maintained exteriors signal lower future maintenance costs and support asking prices
  • Strategic updates to kitchens and bathrooms deliver disproportionate returns relative to investment
  • Lighting, spatial flow, and design coherence influence buyer emotional response and willingness to pay

This is where collaboration with staging professionals becomes a strategic affordability tool rather than a cosmetic luxury. Loand Styles’ expertise in transforming properties through thoughtful interior presentation helps sellers capture maximum value in any rate environment, while buyers working with staged properties can better visualize potential and make confident offers. In markets where affordability constraints limit purchasing power, optimizing sale price through professional presentation creates financial flexibility that compounds over the mortgage’s lifetime, often delivering greater net benefit than waiting for marginal rate improvements.

Comparing Scenarios: Interest Rate vs. Home Price Trade-offs

Consider a straightforward scenario: a $500,000 home at 3% interest versus a $475,000 home at 4%. With a 20% down payment and a 25-year amortization, the monthly payment on the higher-priced home is $1,893, while the lower-priced option costs $1,993. You’d pay $100 more monthly to buy at the lower price with the higher rate, counterintuitive to many buyers who fixate exclusively on purchase price.

The math shifts dramatically when you look beyond the monthly payment to total interest paid. Over 25 years, the $500,000 home at 3% generates $167,900 in interest costs, while the $475,000 home at 4% accrues $218,900, a $51,000 difference favouring the lower rate scenario despite the higher initial price.

To evaluate your own trade-off decisions accurately, follow this calculation sequence:

  1. Calculate the mortgage amount by subtracting your down payment from each purchase price you’re comparing.
  2. Apply the interest rate and amortization period to determine the monthly payment for each scenario using a standard mortgage calculator.
  3. Multiply the monthly payment by the total number of payments to find the lifetime cost.
  4. Subtract the principal from the lifetime cost to isolate total interest paid.
  5. Compare both monthly affordability and long-term interest burden to identify which scenario aligns with your financial priorities.

The relationship between these variables becomes more pronounced at higher price points. A $1,000,000 property at 2.5% with 20% down yields a $3,562 monthly payment, while a $950,000 property at 3.5% costs $3,799. Here, buying at the higher price with the lower rate saves you $237 monthly and $33,000 in total interest over the loan term.

Context matters immensely. If you anticipate refinancing within five years when rates might drop, locking in a lower purchase price today could outweigh the near-term rate disadvantage. Conversely, if you plan to hold the property long-term and rates are at historic lows, though not the case with the current 2.25% policy rate, accepting a higher price to secure that rate makes financial sense.

The decision threshold isn’t universal. A household prioritizing cash flow needs to weight monthly payment differences heavily, making rate changes more impactful than modest price fluctuations. An investor focused on equity accumulation might favour a lower purchase price even if it means higher immediate financing costs, particularly in markets where appreciation expectations justify the trade-off.

What Determines Your Personal Affordability Threshold

Your personal affordability threshold depends on far more than prevailing interest rates or average home prices in your market. Lenders and financial institutions assess a constellation of individual factors to determine how much mortgage debt you can responsibly carry, and understanding these variables gives you control over your borrowing capacity regardless of broader economic conditions.

Income forms the foundation of any affordability calculation. Lenders typically use gross annual income, before taxes and deductions, as the starting point, but they scrutinize income stability and predictability. Salaried employment with consistent pay stubs carries more weight than variable commission income or self-employment earnings, which may require two years of tax returns to verify. In many international markets, particularly across Europe and Asia, lenders apply stricter income documentation standards than Canada, requiring comprehensive employment contracts and bank statements showing regular deposits.

Debt ratios determine the proportion of your income that can service housing costs. The Gross Debt Service (GDS) ratio measures your monthly housing expenses, mortgage payment, property taxes, heating costs, and half of condominium fees, as a percentage of gross income. Most Canadian lenders cap GDS at 32 to 35 percent. The Total Debt Service (TDS) ratio adds all other debt obligations, car loans, student loans, credit card minimum payments, and typically cannot exceed 42 to 44 percent. These thresholds vary internationally; Australian lenders often use more conservative ratios, while some European markets permit higher debt loads for borrowers with exceptional credit profiles.

Down payment size directly affects both approval likelihood and borrowing costs. In Canada, purchases below one million dollars require a minimum five percent down for the first $500,000 and ten percent on the portion above that threshold. Properties over one million require twenty percent down. Larger down payments reduce loan-to-value ratios, often securing better interest rates and eliminating mortgage insurance premiums. In markets like the United Kingdom, twenty-five percent deposits remain common for competitive rates, while New Zealand has progressively tightened deposit requirements in recent years.

Credit profile encompasses your payment history, outstanding balances, and credit utilization patterns. Canadian lenders typically require credit scores above 680 for prime mortgage rates, though borrowers with scores above 750 access the most favorable terms. Credit history length matters, new immigrants or young buyers with limited credit files may face additional documentation requirements or higher rates. International credit histories rarely transfer directly; newcomers to Canada often need to establish domestic credit before qualifying for optimal mortgage terms, though some lenders now consider foreign credit reports with proper translation and verification.

Employment stability influences lender confidence in your ability to maintain payments through economic fluctuations. Continuous employment in the same field for two years or more strengthens applications, while frequent job changes or career transitions may prompt additional scrutiny. Self-employed applicants typically face more rigorous income verification and may need larger down payments to offset perceived risk. In contrast to some European markets where employment contracts provide stronger protections, Canadian lenders focus heavily on income consistency rather than contract type alone.

Lifestyle costs often receive insufficient attention in affordability planning. Transportation expenses, childcare, insurance premiums, savings contributions, and discretionary spending all reduce the income available for housing costs. A conservative affordability framework allocates no more than 28 percent of net, not gross, income to housing, leaving room for unexpected repairs, property tax increases, and life changes. When calculating sustainable housing expenses, consider how your space will function; consulting our virtual styling guide can help you assess whether a smaller, well-designed property might meet your needs better than stretching financially for extra square footage you may not use effectively.

Stress-testing scenarios protects against future rate increases and income disruptions. Calculate your mortgage payment at both the contracted rate and a rate three percentage points higher, the buffer many Canadian lenders now require for qualification. Model payments if one income earner leaves the workforce, if property taxes rise fifteen percent, or if major repairs become necessary. These exercises reveal your true comfort zone rather than your maximum borrowing capacity, a distinction that becomes critical when market conditions shift.

DIY Affordability Analysis vs. Professional Financial Planning

Determining whether you can afford a property starts with basic arithmetic, mortgage calculators and debt-service ratio guidelines give you an initial threshold within minutes. These tools factor in the current 2.25% policy rate environment and provide preliminary estimates of your purchasing range. For straightforward situations, stable income, minimal debt, conventional financing, self-assessment may suffice to establish your comfort zone and begin house hunting.

The limitations emerge when market conditions shift or your financial profile adds complexity. Online calculators cannot anticipate how lenders will interpret your self-employment income, account for variable compensation structures, or advise on optimal down payment strategies when the Bank of Canada announces rate decisions on its scheduled dates throughout 2026. They offer snapshots, not strategies.

Pros

  • DIY tools provide immediate estimates at no cost, useful for initial budgeting and quick market comparisons.
  • Professional advisors offer personalized analysis accounting for income complexity, credit nuances, and optimal timing around rate announcements.
  • Mortgage brokers access multiple lenders and can secure better rates than direct applications, often offsetting their service cost.
  • Real estate agents bring market intelligence on timing and negotiation leverage that calculators cannot replicate.

Cons

  • Self-directed analysis may overlook qualification factors that reduce borrowing capacity or miss rate products suited to your profile.
  • Professional guidance involves upfront time investment and potential fees, though mortgage brokers are typically compensated by lenders.
  • Generic online tools cannot evaluate trade-offs between rate types, amortization periods, or prepayment flexibility specific to your goals.
  • Without expert input, buyers may misjudge optimal purchase timing relative to the Bank of Canada’s announcement schedule.

Professional collaboration becomes essential when affordability sits on the edge of qualification thresholds or when market timing matters significantly to your outcome. A mortgage broker navigates rate negotiations and structures financing to maximize approval odds. Real estate agents identify properties priced below replacement cost or advise when seasonal inventory shifts favour buyers. Staging specialists help sellers position properties to command premium pricing, strategic presentation can sell faster with glam styling, directly affecting the purchase price component of your affordability equation.

The choice isn’t binary. Start with self-assessment to establish parameters, then engage specialists when decisions carry financial weight or timing sensitivity. The cost of professional guidance typically proves modest compared to securing a quarter-point better rate or avoiding an overpriced purchase in a cooling market.

Strategic Timing: Making Interest Rates and Home Prices Work for You

Timing your home purchase requires understanding three converging factors: the Bank of Canada’s announcement schedule, your local market dynamics, and your personal financial readiness. With rate announcements on October 28 and December 9, 2026, still ahead, buyers face decisions about whether to act now at the current 2.25% policy rate or wait for potential changes. The answer depends less on predicting central bank moves and more on coordinating the elements within your control.

If you’re buying in the next six months, lock your mortgage rate as soon as you find a property rather than gambling on future announcements. Most lenders offer 90 to 120-day rate holds, protecting you from increases while allowing you to benefit if rates drop. This removes one variable from your equation. Your negotiation leverage shifts with market conditions, slower markets with higher inventory give buyers pricing power, while competitive markets demand speed and fewer contingencies. Know which environment you’re entering before you structure your offer.

Professional home staging becomes strategic leverage in any market condition. When you’re selling to fund your next purchase, proper staging can reduce time on market by 30 to 50 percent and increase sale prices by 5 to 10 percent, accelerating your timeline and improving your buying position. When you’re purchasing, homes that haven’t been professionally styled often sit longer, creating negotiation opportunities. The seller’s urgency becomes your advantage.

Successful timing emerges from collaboration. Work with mortgage brokers who monitor rate cycles and can time your pre-approval optimally. Partner with agents who read local inventory patterns and know when to move aggressively versus wait. Engage staging professionals early if you’re selling, the weeks spent preparing your home for market can coincide with rate-lock periods, aligning both timelines. You can’t control central bank policy, but you can control preparation, presentation, and the expertise you bring to your transaction.

Common Questions About Housing Affordability and Mortgage Costs

Professionally staged living room with warm golden light and tasteful furnishings
Well-presented interiors can help homeowners maximize perceived value, important when interest rates make budgets tighter.

Should I wait for lower interest rates before buying a home?

Not necessarily. While lower rates improve affordability, home prices often rise when rates drop as more buyers enter the market. Calculate your monthly payment at current rates versus anticipated future scenarios, sometimes buying now at a higher rate but lower price costs less overall, especially if you can refinance later when rates decline.

How much does a 0.25% rate change affect my monthly payment?

On a $500,000 mortgage with a 25-year amortization, a quarter-point rate increase adds approximately $70-75 to your monthly payment. While this seems modest, it compounds over the loan term, that same quarter-point costs roughly $21,000-22,500 in additional interest over 25 years.

Can improving my home’s presentation really offset affordability challenges?

Yes. Professional staging typically returns 5-15% higher sale prices, which directly impacts what you can afford when selling your current property to purchase another. Even strategic updates like 2026 decor accessories and proper styling help properties sell faster and at better prices, giving you stronger negotiating position and more equity to work with.

What’s the best way to calculate how much house I can afford?

Start with the total debt service ratio, your housing costs plus all debt payments shouldn’t exceed 42-44% of gross income. Factor in property taxes, insurance, maintenance, and lifestyle expenses beyond the basic mortgage calculation. Test multiple scenarios with different down payments and rates, and consider getting pre-qualified with a mortgage professional who can stress-test your budget against potential rate increases.

These questions reflect the real concerns buyers face in 2026’s housing market, where the Bank of Canada has held rates at 2.25% through multiple announcement dates. Understanding how rate movements translate to actual payment changes helps you evaluate whether timing your purchase around scheduled rate announcements makes financial sense for your situation.

The relationship between what you qualify for and what you can comfortably afford often differs significantly. Lenders assess your capacity based on debt ratios and credit profile, but only you know your complete financial picture, irregular income patterns, upcoming expenses, career plans, or lifestyle priorities that affect how much housing cost feels sustainable long-term.

Working with professionals who understand both market conditions and property value optimization creates advantages that purely numerical analysis misses. A mortgage broker navigates rate options and timing strategies. A skilled agent identifies properties with negotiation potential. A staging expert maximizes your selling price or helps you recognize value in properties that need presentation improvements. This collaborative approach addresses affordability from multiple angles rather than accepting market conditions as fixed constraints.

The relationship between housing affordability and interest rates isn’t an either-or proposition. Your mortgage payment responds to both variables, and optimizing your position requires evaluating them together rather than fixating on one at the expense of the other. A lower interest rate doesn’t guarantee affordability if home prices have escalated beyond your sustainable debt ratio. Conversely, a modest price decline offers little relief if borrowing costs have climbed sharply.

What separates successful buyers from those perpetually waiting for perfect conditions is recognizing where control actually lies. You can’t dictate the Bank of Canada’s next move from its scheduled announcement dates, nor can you single-handedly shift market-wide pricing trends. But you absolutely can improve your purchasing power through deliberate preparation: strengthening your credit profile, increasing your down payment, securing rate-hold agreements during favorable windows, and working with professionals who understand market timing.

Equally critical is maximizing the value proposition of any property you’re considering. Strategic presentation transforms perceived worth, whether you’re selling to fund your next purchase or evaluating a property’s investment potential. Loand Styles works with clients across diverse budgets and international markets to ensure properties showcase their full potential, creating competitive advantages that transcend temporary rate fluctuations or pricing cycles.

The housing market will continue cycling through periods of varying affordability. Your advantage comes from staying informed about macroeconomic conditions while focusing relentlessly on factors within your control: financial readiness, strategic timing, professional collaboration, and property optimization. Master those elements, and you’ll navigate any combination of rates and prices more effectively than those who simply react to headline changes.

Living room interior with a stone fireplace on one wall and a flat-screen TV on a perpendicular wall, styled for comfortable viewing.

TVs and Fireplaces: Why This Classic Pairing Is Causing Headaches (And How to Get It Right)

Combining TVs and fireplaces in the same room presents a classic design dilemma that homeowners and interior professionals face regularly: how to integrate two competing focal points without compromising aesthetics, safety, or viewing comfort. The most successful approach involves careful placement planning, heat management solutions, and strategic room layout that acknowledges both elements deserve prominence without one dominating the other.

The traditional solution of mounting a television directly above a fireplace, while space-efficient, creates several problems. Heat from the fireplace can damage electronics, viewing angles force necks into uncomfortable positions, and the visual competition between flickering flames and screen content fragments attention rather than creating cohesion. Research consistently shows that optimal TV viewing height places the screen center at seated eye level, typically 42 to 48 inches from the floor, yet fireplace mantels often sit at 54 inches or higher.

Modern design approaches offer better alternatives. Positioning the TV and fireplace on perpendicular walls allows each to serve as a focal point for different seating arrangements, creating distinct zones within the same space. For rooms where adjacent wall placement isn’t possible, recessed fireplace designs with appropriate heat shielding and articulating TV mounts can work, though they require professional installation and careful product selection.

Budget considerations vary widely. Basic solutions like standalone media consoles paired with electric fireplaces start around modest investment levels, while custom millwork integrating both elements with proper ventilation and concealment systems can reach significant budgets. The key lies in understanding your specific space constraints, usage patterns, and willingness to prioritize function over convention.

The Evolution of TVs and Fireplaces in Modern Interiors

A decade ago, the question of where to put the television barely registered on most homeowners’ radar, it went above the fireplace by default, often because builders had already run the cables there. Fireplaces anchored living rooms as they had for centuries, and mounting the TV on that prominent wall seemed logical, even inevitable. Fast-forward to 2026, and this pairing has become one of interior design’s most debated topics, with perspectives shifting dramatically across different markets and design philosophies.

The transformation began around 2015, when designers and ergonomics specialists started publicly questioning the above-fireplace placement that had become residential standard practice. Scandinavian and Japanese interiors led a counter-movement, treating the fireplace as a meditative element and positioning screens on perpendicular walls or in dedicated media zones. Meanwhile, North American and Australian markets remained committed to the stacked arrangement, viewing it as a space-efficient solution that preserved open floor plans.

Successful integration of televisions and fireplaces reflects deeper cultural values, whether a home prioritizes communal entertainment or quiet contemplation as its primary gathering function.

European approaches further complicated the conversation. British and French designers often favored preserving the fireplace as the sole focal point, relegating televisions to secondary positions or hiding them in cabinetry. German and Dutch markets embraced minimalist solutions that treated both elements with equal restraint, frequently recessing screens into millwork to minimize visual competition.

By the early 2020s, property staging revealed telling patterns: homes marketed to traditional buyers still showcased the TV-over-fireplace layout, while luxury properties increasingly demonstrated alternative configurations as markers of sophisticated design thinking. This bifurcation continues in 2026, with mounting preferences now serving as subtle indicators of design philosophy rather than mere convenience. The evolution hasn’t resolved the debate, it has simply expanded the range of acceptable solutions, making thoughtful placement more important than ever.

The Real Problems with Mounting Your TV Above the Fireplace

A flat-screen TV mounted above a stone fireplace in a modern living room
A modern room setup shows the classic “TV above fireplace” look and the visual tension it can create.

Heat and Technical Considerations

Close view of a TV mounted above a fireplace showing the height and proximity relationship
A detailed view highlights the proximity between TV and fireplace that can affect safe clearances and comfort.

Heat poses a genuine threat to television electronics, regardless of how elegant the installation appears. Modern TVs contain sensitive components that manufacturers typically rate for operation between 0°C and 40°C (32°F to 104°F). Above a fireplace, temperatures can easily exceed these limits, particularly with wood-burning units that radiate intense heat upward.

Wood-burning fireplaces present the highest risk, generating temperatures of 200°C (400°F) or more near the opening. Gas fireplaces produce less heat but still create significant thermal stress, while electric units offer the most TV-friendly option with minimal heat output and controlled ventilation.

Safe clearance varies by fireplace type. For wood-burning installations, maintain at least 36 inches between the mantel and screen bottom, though 48 inches proves safer. Gas fireplaces require minimum 24-inch clearance, while electric units may permit closer mounting if venting allows.

Mitigation strategies include installing a mantel shelf to deflect rising heat, adding insulation behind the TV mounting area, or incorporating ventilation systems that actively cool the space. Heat shields designed specifically for this application can redirect thermal currents, though they rarely eliminate risk entirely. Professional installers should measure actual operating temperatures before finalizing any above-fireplace TV placement, regardless of clearance calculations.

Viewing Comfort and Ergonomics

The standard viewing guideline, eye level when seated, places optimal TV height between 42 and 53 inches from the floor. Above-fireplace mounting typically positions the screen 60 to 70 inches high, forcing viewers to tilt their heads back 15 to 30 degrees. Extended viewing at these angles creates neck tension, shoulder strain, and eye fatigue within an hour.

Research confirms viewing discomfort increases significantly when screens sit more than 10 degrees above eye level. Mantels at 54 inches combined with 55-inch televisions place the screen centre at roughly 81 inches, well into the discomfort zone. The farther you sit from the screen, the worse this angle becomes; distance creates steeper upward sightlines rather than mitigating them.

Room proportions matter enormously. Low ceilings exaggerate proportion issues and make elevated mounting feel oppressive. Seating distance compounds the problem: furniture pushed too far back to accommodate viewing angles sacrifices conversational intimacy, while sitting closer to reduce neck strain makes the screen overwhelming.

If your fireplace mantel exceeds 50 inches and you watch television regularly rather than occasionally, mounting above creates ergonomic problems no amount of styling can solve. Comfort drives functionality, and strained viewing positions undermine both.

Visual Balance and Proportion

Visual Balance and Proportion

Mounting a television above a fireplace creates immediate scale problems. Most modern TVs measure 55 to 75 inches diagonally, forming a dominant black rectangle that often dwarfs the fireplace below. This imbalance becomes particularly pronounced with traditional mantels, where ornate architectural details compete unsuccessfully for attention against the screen’s flat expanse.

The mantel itself presents styling challenges. Decorative objects that work beautifully alone, candlesticks, vases, framed photographs, appear cluttered and insignificant beneath a large TV. The screen’s visual weight pulls the eye upward, making anything placed on the mantel feel like an afterthought rather than intentional design.

Creating a cohesive focal point requires careful consideration of proportions. A fireplace surround needs sufficient visual presence to anchor the TV without overwhelming the space. Wide, simple mantels in contemporary materials like limestone or concrete can support larger screens better than narrow Victorian-era designs. The relationship between fireplace width and TV width matters significantly; designers typically recommend the screen span no more than two-thirds the width of the fireplace opening to maintain balance.

When both elements occupy the same vertical space, neither functions as an effective focal point. Instead, they create visual competition that fragments attention and undermines the room’s overall composition.

Smart Mounting Solutions for 2026

Motorized and Adjustable Mounting Systems

Motorized mounts offer a practical compromise for homes where placing TVs above fireplaces remains the only viable option. Pull-down mechanisms allow the screen to descend from its decorative position to eye level for comfortable viewing, then retract when not in use. These systems maintain the clean aesthetic many homeowners desire while addressing ergonomic concerns. Prices range from approximately £400 for basic manual pull-down models to £2,500+ for fully motorized systems with remote control.

Articulating arm mounts provide another solution, extending forward and tilting downward to improve viewing angles from seating areas. Quality articulating mounts support screens up to 75 inches and offer smooth adjustment, though they protrude noticeably when deployed. Professional installation is essential, as these systems require robust wall anchoring to support the extended weight safely.

For those pursuing seamless integration, TV lift mechanisms concealed within custom cabinetry or behind artwork represent the premium solution. The television rises from within the mantel or drops from a ceiling recess at the touch of a button, completely disappearing when not needed. While these installations typically start around £3,000 excluding cabinetry work, they deliver the dual focal point elegance that high-end residential and staging projects demand.

Built-In and Custom Solutions

Custom millwork represents the most elegant approach to harmonizing TVs and fireplaces, creating architectural solutions that feel intentional rather than forced. A recessed media wall with built-in cabinetry can lower the television to proper viewing height while maintaining visual connection with the fireplace below, transforming two competing elements into a unified focal point.

Floor-to-ceiling millwork surrounding both fireplace and TV allows designers to control proportions, integrate hidden cable management, and provide flanking storage that balances the composition. These installations work particularly well in new construction or major renovations where structural modifications are feasible.

Budget expectations vary significantly by project scale. Simple painted MDF surrounds with basic recesses start around $3,000, $5,000, while fully custom hardwood installations with sophisticated lighting and concealed mounts range from $15,000, $40,000 or more. International projects may see different price points based on local labor costs and material availability.

The investment pays dividends in resale value and daily enjoyment. Well-executed built-ins eliminate the awkward “TV stuck above fireplace” look entirely, creating architecture that serves both functions without compromise. For clients committed to keeping both elements in the same sightline, custom solutions deliver results that retrofit hardware simply cannot match.

Alternative Configurations That Work Better

A motorized TV integrated into custom wood millwork above a fireplace with the screen lowered
The TV solution is integrated into custom millwork so it can be adjusted for better viewing while keeping the fireplace as the centerpiece.

When the traditional above-the-fireplace mounting doesn’t work for your space, several smarter configurations can give you both a functional media center and a beautiful fireplace without forcing them into an awkward marriage.

The most straightforward alternative is placing your TV on an adjacent wall perpendicular to the fireplace. This arrangement lets each element breathe as its own focal point while keeping both fully functional. In many living rooms, this creates natural conversation zones, one centered on the fireplace for intimate gatherings, another oriented toward the TV for entertainment. The key is arranging furniture to accommodate both viewing scenarios, typically with a sectional or swivel chairs that can pivot between the two areas. This layout works particularly well in larger rooms where you have wall space to spare and can establish distinct zones without the room feeling fragmented.

Note: The most successful room layouts don’t try to make one focal point dominate, they create intentional zones where each element serves a specific purpose without competing for attention.

Side-by-side placement on the same wall offers another elegant solution, particularly when you have a wide enough span to maintain proper proportions. Built-in cabinetry or millwork that frames both elements creates visual unity while keeping the TV at proper eye level. This approach works best with linear fireplaces or when you can design the architecture from scratch to accommodate both. The fireplace might occupy one third of the wall while the TV and surrounding storage take the remaining space, creating a balanced media wall that feels intentional rather than compromised.

For rooms with limited wall options, consider placing the TV in a built-in unit on the wall opposite the fireplace. Yes, this means your back is to the fireplace while watching television, but it positions the screen at optimal height and viewing distance. During non-viewing hours, the fireplace remains the room’s visual anchor. This configuration is common in European design, where fireplaces often occupy prominent positions while televisions are treated as functional equipment to be concealed when not in use.

Corner fireplaces present unique opportunities for diagonal furniture arrangements that orient seating toward both elements without stacking them vertically. The TV can go on an adjacent wall at proper height while the angled fireplace maintains its presence as an architectural feature. This layout maximizes usable floor space in smaller rooms while solving the dual-focal-point challenge.

Making It Work: Professional Guidelines for Success

When mounting above a fireplace is truly your only viable configuration, professional execution becomes essential. Start by assembling the right team: a licensed electrician to ensure safe power routing away from heat zones, an experienced installer familiar with fireplace-specific mounting requirements, and ideally a designer who understands both technical constraints and visual proportion. This collaborative approach prevents costly mistakes and ensures the installation meets safety standards while achieving a polished result.

Specify a minimum 12-inch clearance between the fireplace opening and the TV bottom edge, more for wood-burning units. Install a proper mantel or heat shield if one doesn’t exist; this physical barrier deflects rising heat and protects your investment. Insist on a full-motion mount that allows downward tilting of at least 15 degrees, reducing neck strain during extended viewing. This adjustment makes a significant difference in comfort, particularly in rooms where seating is fixed.

Budget for professional installation rather than attempting DIY. Installers experienced with fireplace mounts understand how to locate studs around masonry, run concealed wiring that meets code, and position the screen at the optimal compromise height. Expect to invest between $300 and $800 for professional mounting services, depending on complexity and regional rates. Custom millwork to frame the TV and create visual cohesion adds another $1,500 to $5,000, but transforms an awkward pairing into an intentional design feature.

For properties being prepared for sale, consider how this setup reads to potential buyers. Home staging professionals often recommend neutral, low-profile screens and uncluttered mantels that don’t distract from the architecture itself. Remote virtual styling consultations can provide objective perspective on whether your current configuration enhances or detracts from the room’s overall appeal, offering cost-effective guidance before committing to permanent installations.

Styling and Staging Considerations

When staging properties for sale, the relationship between TVs and fireplaces becomes a strategic decision rather than a lifestyle choice. Professional stagers routinely remove or conceal televisions entirely when preparing homes for market, recognizing that buyers need to envision their own lives rather than focus on the seller’s entertainment setup. This approach helps properties sell faster by eliminating the visual clutter and dated mounting choices that can age a space.

Property Type TV Approach Fireplace Styling
Owner-Occupied Home Prominent, optimized for daily viewing comfort Secondary to TV function; mantel styled around screen presence
Luxury Market Staging Concealed in millwork or frame mounts; lifestyle imagery emphasized Primary focal point with curated art and minimal decor accessories
Quick-Sale Staging Removed entirely; wall left neutral or decorated as gallery space Styled to showcase architectural appeal with budget-friendly seasonal vignettes

International staging trends reveal diverging philosophies. European markets typically favor minimalist decor that positions the fireplace as an architectural statement, often leaving walls above mantels bare or featuring single pieces of original art. North American staging leans toward lifestyle vignettes that balance technology acknowledgment with aspiration. Australian and New Zealand stagers frequently highlight outdoor views through strategic furniture placement, allowing fireplaces to anchor conversation zones while keeping screens peripheral.

For permanent residences, our approach at Tarlo & Graham centers on collaboration between homeowners’ daily habits and long-term design integrity. We work with clients to create flexible solutions where technology enhances rather than dominates, frame TVs that display artwork when idle, motorized lifts concealed within custom cabinetry, or room layouts that give equal importance to both elements without forcing one above the other. The goal is always balance: spaces that function beautifully for real life while maintaining the timeless elegance that makes a house feel like a carefully considered home.

The relationship between TVs and fireplaces doesn’t have to be adversarial. With careful planning and an honest assessment of your space, these two elements can coexist beautifully without sacrificing comfort or style.

Success starts with asking the right questions early. What’s the primary function of the room? How do you actually use the space? What’s your budget for both installation and potential custom solutions? These answers, combined with professional input from designers and installers, will guide you toward a configuration that works for your specific situation rather than following a trend that may not suit your home.

Remember that the “right” solution varies dramatically from one space to another. A period property in London requires different considerations than a new-build apartment in Sydney. A family media room has different priorities than a formal living space being staged for sale. There’s no universal formula, and that’s precisely why cookie-cutter approaches so often disappoint.

Whether you choose a traditional above-mantel mount with proper heat shielding, invest in a motorized system that adjusts for optimal viewing, or opt for an alternative layout that gives each element its own moment to shine, the key is intentionality. Make decisions based on how you live, not just how a room photographs.

The best integration of TVs and fireplaces is one that serves your lifestyle first, respects the architecture of your space, and brings you genuine pleasure every time you walk into the room.

Mortgage planning scene with a Nova Scotia home reflection on a tablet and blank paperwork on a desk against a soft coastal background.

How Much Are Mortgage Rates in Nova Scotia? (2026 Guide)

As of August 2026, mortgage borrowers in Nova Scotia can secure variable rates starting at 3.4% and fixed rates from approximately 4%, with the five-year variable benchmark at 3.60% from lenders including Bank of Montreal and Pine Financial. The five-year fixed insured rate currently sits at 4.04%. These figures reflect the Bank of Canada’s overnight rate target of 2.25%, set as of July 15, 2026, a critical anchor point that shapes every mortgage conversation in the province.

Key Takeaway: Variable rates in Nova Scotia start at 3.4%, fixed rates begin around 4%, and the Bank of Canada’s benchmark rate stands at 2.25% as of July 2026. Your final rate depends on term length, down payment size, and lender selection.

What separates a competitive rate from an expensive one? Three levers dominate: the type of rate you choose (fixed or variable), your mortgage term, and your insured versus conventional status. A 20% down payment typically unlocks better pricing than a 5% down scenario. Lender relationships matter, too. Credit unions, major banks, and mortgage brokers each bring different rate cards and approval appetites to the table.

Understanding these rates is more than a financing exercise. It’s a foundational step in any property decision, whether you’re purchasing your first Halifax condo, staging a heritage home in Lunenburg to maximize resale value, or advising clients on investment-worthy renovations. Just as savvy designers mix old and new elements to create timeless interiors, informed borrowers blend rate strategy with long-term property vision. The mortgage you choose today shapes the home you can afford tomorrow and the equity you build over decades. In a province where coastal charm meets vibrant urban growth, every percentage point carries real weight.

Current Mortgage Rates in Nova Scotia: What You’ll Pay in 2026

Couple holding house keys while seated indoors near a bright window
A homebuyer moment with keys in hand helps set the emotional context for mortgage-rate decisions in Nova Scotia.

As of August 5, 2026, Nova Scotia homebuyers can access competitive mortgage rates that vary significantly based on the product type and term you select. Variable-rate mortgages currently offer the lowest entry point, with rates as low as 3.4%, while fixed-rate options generally start around 4%. These rates reflect the Bank of Canada’s current overnight rate target of 2.25%, set on July 15, 2026.

The most competitive offerings in the market today include 5-year variable mortgages at 3.60% from both Bank of Montreal and Pine Financial, providing stability in term length while allowing your rate to adjust with market conditions. For borrowers prioritizing predictability, Canada’s lowest insured 5-year fixed mortgage rate sits at 4.04%, offering payment certainty through 2031.

Rate Type Term Length Current Rate Example Lender
Variable 5-year 3.60% Bank of Montreal
Variable 5-year 3.60% Pine Financial
Fixed (Insured) 5-year 4.04% Various
Fixed Shorter terms From 4.00% Multiple lenders

The gap between variable and fixed rates creates a meaningful difference in your monthly payment. On a $400,000 mortgage with a 25-year amortization, the difference between a 3.60% variable rate and a 4.04% fixed rate translates to roughly $100 less per month with the variable option. However, variable rates carry the risk of increases when the Bank of Canada adjusts its overnight rate, which happens on eight predetermined dates throughout the year.

Your actual rate will depend on factors beyond just the current market averages, including whether you’re making a down payment large enough to avoid mortgage insurance, your credit profile, and the lender you choose. Shopping across banks, credit unions, and mortgage brokers helps you capture the best available rate for your specific situation.

Mortgage Rates by Type and Term Length

Fixed-Rate Mortgages in Nova Scotia

Fixed-rate mortgages lock your interest rate for the entire term, which means your payments stay the same regardless of what happens with the Bank of Canada’s overnight rate. In Nova Scotia as of August 2026, you’ll find fixed rates starting around 4%, with the lowest insured 5-year fixed sitting at 4.04%.

The choice between 1-year, 2-year, and 5-year terms affects both your rate and your total interest costs. Shorter terms like 1-year fixed typically offer slightly lower rates but require renewal sooner, exposing you to potential rate increases when your term ends. A 2-year fixed splits the difference, giving you moderate predictability without committing to a full five years. The 5-year term remains the most popular option because it provides payment certainty through a complete cycle of potential rate adjustments.

On a $300,000 mortgage at 4.04%, you’d pay roughly $1,415 monthly over a 25-year amortization. That same mortgage at 4.5% costs about $1,667 monthly. Over five years, the difference between these rates amounts to approximately $15,120 in total payments. Fixed rates suit buyers who value budgeting certainty and want protection against rising rates, particularly when planning property improvements or staging investments that require predictable cash flow.

Variable-Rate Mortgages in Nova Scotia

Variable rates in Nova Scotia currently start as low as 3.4%, offering immediate savings compared to fixed options. As of August 5, 2026, major lenders including Bank of Montreal and Pine Financial are offering 5-year variable mortgages at 3.60%, roughly 0.44 percentage points below the lowest available 5-year fixed rate.

These rates aren’t locked in. They move in step with the Bank of Canada’s overnight rate, which sits at 2.25% as of July 15, 2026. The central bank reviews this benchmark eight times annually, and when it shifts, your rate and payment adjust accordingly, usually within one billing cycle.

The trade-off is straightforward. You’ll pay less today, but you’re exposed to increases if the Bank of Canada raises rates. On a $400,000 mortgage, the difference between a 3.60% variable and a 4.04% fixed rate means roughly $100 less per month initially. Over five years, that gap can amount to substantial savings if rates hold steady or decline, but it narrows or reverses if rates climb.

Variable products suit borrowers who can absorb payment increases and believe rates will stabilize or drop. If you value predictability over potential savings, or if your budget is already stretched, the fixed route offers more security even at a higher entry point.

What Determines Your Mortgage Rate

Calculator and planner on a staged living room sofa with soft natural light
A staged home scene with everyday finance tools conveys how mortgage rates influence real purchasing plans.

Your mortgage rate in Nova Scotia isn’t plucked from thin air. Lenders calculate what you’ll pay based on a combination of market conditions, your financial profile, and the specific mortgage product you select. Understanding these variables helps you anticipate the rate you’ll qualify for and identify where you might have leverage to negotiate a better deal.

The foundation of all mortgage pricing starts with the Bank of Canada target rate which stood at 2.25% as of July 15, 2026. This overnight rate, adjusted eight times annually on predetermined dates, influences what lenders pay to borrow money themselves. When the central bank raises or lowers this benchmark, mortgage rates typically follow within days or weeks. Your 3.60% variable rate exists because lenders add a margin above this base cost to cover their risk and profit.

Several interconnected factors determine the specific rate a lender offers you:

  • Rate type selection: Fixed rates (starting around 4% in August 2026) cost more than variable options (as low as 3.4%) because you’re paying for payment certainty
  • Term length: Shorter terms like 1-year mortgages often carry lower rates than 5-year products, reflecting reduced lender risk exposure
  • Down payment size: Mortgages with less than 20% down require insurance and typically qualify for insured rates (currently 4.04% for 5-year fixed), which can be lower than conventional rates
  • Lender competition: Banks, credit unions, and private lenders price differently; BMO and Pine Financial both offer 3.60% on 5-year variable products, but dozens of institutions compete across the spectrum
  • Credit profile: Your score, income stability, debt ratios, and employment history directly affect perceived risk and rate eligibility
  • Property type: Owner-occupied homes receive better rates than investment properties or unique builds that are harder to resell
  • Economic conditions: Inflation expectations, bond yields, and housing market strength create the broader rate environment lenders operate within

The interplay matters more than any single factor. A buyer with 25% down and excellent credit might secure a rate 0.5 percentage points lower than someone borrowing 95% of the purchase price, even on identical properties. Term selection compounds this: choosing a 5-year fixed at 4.04% versus a 5-year variable at 3.60% means paying an extra 0.44% annually for rate protection, a premium some buyers gladly accept while others view as unnecessary cost.

Lender choice creates surprising variation. While major banks advertise headline rates, smaller institutions and mortgage brokers often access wholesale pricing or promotional offers that shave 0.10% to 0.30% off your cost. This explains why comparing quotes from multiple sources before committing is standard practice among experienced buyers and the real estate professionals who guide them through financing decisions.

Breaking Down Your Mortgage Costs Beyond the Rate

The advertised mortgage rate tells only part of your financing story. A 4% fixed rate or 3.4% variable rate determines your interest expense, but your actual cash outlay includes several additional layers that can add thousands to your total investment.

Your monthly mortgage payment splits into two components: principal (the amount you borrowed) and interest (the cost of borrowing). On a $300,000 mortgage at 4% over 25 years, you’ll pay roughly $1,580 monthly, with about $1,000 going to interest in the first year and the rest reducing your loan balance. Variable rates around 3.6% lower that payment to approximately $1,520, but the split changes as rates adjust with Bank of Canada decisions.

Beyond these recurring payments, mortgage acquisition involves one-time closing costs that typically range from 1.5% to 4% of the purchase price:

  1. Legal fees and disbursements ($1,200, $2,500) cover your lawyer’s work preparing documents, conducting title searches, and registering the mortgage
  2. Home appraisal ($300, $500) provides the lender with an independent property valuation to confirm the loan amount
  3. Title insurance ($250, $400) protects against ownership disputes or title defects
  4. Property tax adjustments reimburse the seller for prepaid taxes from the closing date forward
  5. Mortgage default insurance premiums (0.6%, 4.5% of the loan) apply if your down payment sits below 20%, often added to the mortgage rather than paid upfront

On a $400,000 home purchase, these closing costs alone can reach $8,000, $16,000 before you make your first payment.

The connection between mortgage approval and property presentation often gets overlooked. Lenders base their valuation on current property condition, which directly affects the loan amount you qualify for. Strategic investment in professional staging before appraisal can increase perceived market value, potentially securing a higher approved amount or avoiding low-appraisal complications. Incorporating aged and styled pieces creates visual warmth that appraisers and buyers respond to, especially in Nova Scotia’s competitive markets where well-presented homes command premium valuations. This preparation cost, typically 1%, 3% of listing price, can yield returns that more than offset the expense through improved financing terms and faster sales.

Working with Mortgage Brokers vs. Direct Lenders

When you’re navigating Nova Scotia’s mortgage market in 2026, you face a fundamental choice: work with a mortgage broker who shops multiple lenders on your behalf, or approach banks and credit unions directly. Each path has distinct advantages depending on your financial situation, time availability, and comfort with the mortgage process.

Mortgage brokers act as intermediaries who compare rates and products across dozens of lenders, often accessing wholesale rates unavailable to individual applicants. They handle the paperwork, negotiate terms, and guide you through qualification requirements without charging you directly, lenders pay their commission. This mirrors how professional home staging services provide expertise that individual sellers rarely possess, transforming properties through strategic design choices that maximize market appeal.

Direct lender applications give you complete control over the process and allow you to leverage existing banking relationships. If you’re already a customer with a strong deposit history or investment portfolio, your bank may offer preferential rates or expedited approval. You’ll also deal with one institution throughout the mortgage term, simplifying future refinancing or renewal discussions.

Pros of Using a Mortgage Broker

  • Access to rates from 30+ lenders compared to one institution’s offerings.
  • Professional negotiation often secures lower rates than individual applicants achieve.
  • Brokers handle complex situations like self-employment income or credit challenges more effectively.
  • No direct cost to you, as lenders pay the broker commission.

Cons of Using a Mortgage Broker

  • Brokers may prioritize lenders offering higher commissions rather than your absolute best rate.
  • You sacrifice the relationship continuity that comes with direct bank contact.
  • Some specialty programs or niche products remain exclusive to specific institutions.

The time investment differs substantially between approaches. Brokers streamline the process by submitting your application to multiple lenders simultaneously, often delivering rate comparisons within 48 hours. Direct applications require you to research options, visit multiple branches, and negotiate independently, potentially taking weeks to evaluate all available products thoroughly.

Consider this parallel: just as a virtual styling service provides design expertise that transforms spaces more effectively than DIY attempts, mortgage brokers bring market knowledge and negotiating power that individual borrowers rarely match. The cost implications extend beyond the rate itself. Brokers typically close deals faster, reducing the risk of rate increases during extended application periods, while their lender relationships can smooth approval for buyers with non-traditional income sources or smaller down payments, factors that directly affect whether you secure financing on your desired property at optimal terms.

How Mortgage Rates Impact Your Home Investment Strategy

Mortgage broker and client reviewing notes at an office desk
A broker-client conversation illustrates expert guidance without showing any readable numbers or text.

Today’s Nova Scotia mortgage rates, fixed options around 4% and variable rates as low as 3.4%, do more than determine your monthly payment. They shape what you can afford, which properties make financial sense, and how you position your home as an asset within a broader investment strategy.

When rates sit in the current range, buyers gain purchasing power compared to the higher-rate environment of previous years. A homeowner securing a 3.60% variable rate can afford approximately 15% more house than someone locked into 6% financing, assuming the same monthly budget. That expanded range opens access to better neighborhoods, larger properties, or homes with features that command stronger resale premiums. Smart investors recognize this window and move quickly, knowing rates can shift with the Bank of Canada’s eight annual adjustments.

But purchasing power alone doesn’t guarantee a sound investment. The real value comes from pairing favorable financing with strategic property preparation. Professional home staging and thoughtful styling create measurable returns by reducing time on market and increasing final sale prices, often by 5 to 10% above comparable unstaged listings. When you factor in that mortgage interest compounds over decades, even a modest bump in sale price can offset years of financing costs. A minimalist home decor approach, for example, helps buyers envision themselves in the space, accelerating offers and strengthening negotiating positions.

This collaborative approach, homeowners working with real estate agents and styling professionals, turns mortgage financing from a simple transaction into a coordinated investment strategy. The goal isn’t just securing the lowest rate; it’s maximizing the spread between what you pay to borrow and what the market will pay for a well-presented, move-in-ready property. In competitive international markets, this integrated thinking separates properties that languish from those that sell fast at premium prices.

What Changes the Price

Close view of stone foundation blocks supporting a wooden beam at golden hour
A foundation-and-support concept visually reinforces how mortgage rates ultimately determine long-term stability and investment confidence.

Broader economic forces and individual borrower circumstances both shape the mortgage rates available to Nova Scotia homebuyers. The Bank of Canada’s overnight rate, currently 2.25% as of July 15, 2026, sets the baseline cost of borrowing for lenders. When the central bank adjusts this benchmark on its eight fixed dates annually, lenders typically adjust their prime rates within days, which directly affects variable mortgages and influences fixed-rate pricing.

Your personal financial profile creates the second layer of rate determination. Credit scores above 680 unlock preferential pricing, while scores below 620 trigger risk premiums. Down payment size matters significantly: putting down 20% or more eliminates insurance requirements and qualifies you for lower rates, whereas high-ratio mortgages with smaller down payments carry mandatory insurance costs that lenders often offset with slightly higher rates.

Competitive positioning among lenders drives rate fluctuations too. Major banks, credit unions, and private lenders adjust pricing based on their appetite for new business and market share goals. This explains why identical borrowers receive different rate quotes across institutions, a mortgage broker can leverage these differences to your advantage, much like how consulting professionals about everlasting decor styles helps maximize your property’s market appeal and eventual resale value when refinancing becomes necessary.

Frequently Asked Questions About Nova Scotia Mortgage Rates

Q: What’s the difference between fixed and variable mortgage rates?

Fixed rates lock in your interest cost for the entire term, currently around 4% for five-year products in Nova Scotia, giving you predictable payments regardless of Bank of Canada adjustments. Variable rates, starting as low as 3.4%, fluctuate with the lender’s prime rate, which tracks the overnight rate; you might save money when rates drop, but your payment can increase if the Bank raises rates on one of its eight annual decision dates.

Q: Can I negotiate my mortgage rate in Nova Scotia?

Yes, posted rates are rarely the best offer. Lenders often provide discounts of 0.10% to 0.50% or more when you ask directly or work with a mortgage broker who negotiates on your behalf across multiple institutions. Your credit score, down payment size, and whether you’re bringing other business (like chequing accounts or investments) all strengthen your position.

Q: How does the Bank of Canada’s rate affect my mortgage?

The Bank of Canada’s overnight rate, currently 2.25% as of July 15, 2026, influences what lenders charge. When the Bank increases this target, variable mortgage rates typically rise within days, and fixed rates often adjust upward as bond yields respond. The Bank reviews the rate eight times per year, making variable mortgages more sensitive to economic shifts than fixed products.

Q: When should I lock in a fixed rate versus choosing variable?

Lock in a fixed rate if you value payment certainty and believe the Bank of Canada will raise rates over your term, or if even small monthly increases would strain your budget. Choose variable if you can absorb potential payment changes and think rates will stay flat or decline; historically, variable has saved borrowers money over longer periods, though individual timing matters.

Comparing offers from multiple lenders before committing gives you leverage. Mortgage brokers access wholesale rates not always posted publicly, and they can explain trade-offs between promotional rates (which may carry restrictions) and standard products with flexible prepayment terms. Just as collaborating with a staging professional maximizes your property’s market value, working with an experienced mortgage advisor helps you secure financing terms that align with your investment timeline and risk tolerance across changing rate environments.

Nova Scotia’s mortgage market in 2026 offers competitive options for strategic buyers, with variable rates as low as 3.4% and fixed rates starting around 4%. Your best rate depends on comparing lenders, from major banks like BMO to specialized lenders such as Pine Financial, and choosing the right combination of rate type and term length for your financial situation.

Securing favorable financing is only half the equation. Smart property investment in our international market means thinking beyond the monthly payment to the home’s complete value proposition. When you collaborate with experienced real estate agents and professional styling teams, you create market-ready properties that command higher resale values, effectively offsetting your borrowing costs. A well-staged home doesn’t just sell faster, it often appraises higher, potentially improving your loan-to-value ratio and unlocking better rate tiers.

Whether you’re a homeowner preparing to purchase, a developer planning your next project, or an agent guiding clients through competitive bidding, the interplay between smart financing and elegant presentation defines successful outcomes. Take time to shop multiple lenders, understand how rate types align with your timeline, and invest in the professional expertise that transforms houses into compelling homes buyers will pay premium prices to own.

A Canadian first-time buyer couple holds house keys in front of a modern suburban home exterior in soft daylight.

How Much Do Mortgage Rates for First Time Buyers Cost? (in 2026)

Mortgage rates for first-time buyers in Canada currently range from 3.40% to 4.86%, depending on whether you choose a fixed or variable term and the size of your down payment. As of mid-July 2026, insured mortgages (those with less than 20% down) are attracting some of the most competitive offers in the market, with select lenders like nesto advertising 5-year variable rates as low as 3.40% and 5-year fixed rates at 4.09%. Major banks including RBC, CIBC, and TD are offering insured 5-year fixed rates between 4.61% and 4.86%, while uninsured rates typically sit 10 to 35 basis points higher.

Key Takeaway: First-time buyers with less than 20% down can access lower insured mortgage rates in 2026, with 5-year variable rates starting at 3.40% and fixed options from 3.99%. Limited-time promotional offers, including RBC’s up to $5,900 value package available until August 31, 2026, make this an opportune moment to enter the market.

The gap between what you’ll pay and what your neighbour secured often comes down to four critical factors: your credit score, the size of your down payment, whether you’re buying a resale home or new construction, and crucially, how the property appraises. A home that presents well and shows strong staging can influence appraisal values, affecting not just your loan-to-value ratio but your qualification for preferred rates. Banks see a thoughtfully presented property as a lower-risk asset, which translates directly to better terms for you as the borrower.

Variable rates currently offer the steepest discounts, with Prime minus 1.05% translating to approximately 3.40% based on the Bank of Canada’s current policy environment. Fixed rates provide payment certainty but command a premium, typically 50 to 70 basis points higher. Your choice between these structures should reflect both your risk tolerance and your cash flow stability, particularly during the first years of ownership when other home-related expenses emerge unexpectedly.

Current Mortgage Rates by Term and Type

A first-time homebuyer couple looking around a staged living room while holding a key during a home showing.
A staged home showing captures the confidence first-time buyers feel when touring a property that feels move-in ready.

Fixed-Rate Mortgages

As of July 2026, first-time buyers can access fixed-rate mortgages ranging from 3.89% to over 6%, depending on term length and lender. The 3-year fixed rate sits at approximately 3.89%, while 5-year fixed options cluster between 3.99% and 4.86%, with insured mortgages (requiring less than 20% down and CMHC insurance) typically qualifying for lower rates than uninsured products. The Bank of Canada’s posted fixed mortgage rates currently stand at 6.09% for 5-year terms, though competitive market rates run substantially lower, major banks offer insured 5-year fixed rates between 4.61% and 4.86%.

Fixed rates deliver payment certainty: your monthly principal and interest remain constant throughout the term, insulating you from rate fluctuations when the Bank of Canada adjusts policy. This predictability proves valuable for first-time buyers establishing budgets, managing new homeownership expenses, and protecting against rising rates. You lock in today’s rate for the full term, which means if rates climb, you continue paying your contracted rate. The trade-off is less flexibility than variable products and potentially higher starting rates, but many first-time buyers prioritize the security of knowing exactly what they’ll pay month after month.

Variable-Rate Mortgages

Variable-rate mortgages currently offer first-time buyers rates between 3.40% and 3.65%, making them the lowest-cost borrowing option available in July 2026. These rates fluctuate with the Bank of Canada policy rate which stands at 2.25% as of July 15, 2026. Lenders price variable rates as discounts from their prime rate, for instance, nesto’s 3.40% five-year variable represents prime minus 1.05%.

The appeal is clear: you could save roughly 0.50% to 0.70% compared to equivalent fixed terms right now. On a $400,000 mortgage, that translates to approximately $165 less per month than a 4.09% fixed rate. However, your payment will shift if the central bank adjusts rates at future announcements. If you have stable income and can absorb potential increases of $50 to $100 monthly without strain, the initial savings often justify the uncertainty. First-time buyers stretched thin on affordability might find fixed rates worth the premium for predictable budgeting, while those with financial cushion can capitalize on today’s lower variable environment.

What Changes Your Mortgage Rate

Close-up of mortgage documents, a pen, and a phone calculator on a desk for rate planning.
This scene represents the paperwork and rate research first-time buyers do while planning their mortgage decisions.

Down Payment Impact on Rates

Your down payment size fundamentally determines which mortgage category you qualify for and directly impacts the rate you’ll receive. Put down less than 20% of the purchase price, and you’ll need mortgage default insurance through CMHC, Sonder, or Canada Guaranty, this creates what lenders call a “high-ratio” or insured mortgage. Come to the table with 20% or more, and you enter the uninsured conventional mortgage territory.

Here’s where it gets interesting: insured mortgages often carry lower rates despite requiring insurance. Why? The insurance transfers default risk away from the lender, making these loans less risky from their perspective. Current July 2026 data illustrates this clearly. BMO offers 4.76% on insured mortgages versus 4.86% uninsured, a 0.10% spread. CIBC shows a more pronounced gap at 4.61% insured compared to 4.96% uninsured, a difference of 0.35%. RBC similarly prices insured mortgages at 4.62% while uninsured sit at 4.92%.

That said, your insurance premium (ranging from 2.80% to 4.00% of your mortgage amount depending on down payment size) gets added to your principal, increasing your total loan. A first-time buyer putting down 10% pays 3.10% in insurance fees, on a $400,000 mortgage, that’s $12,400 added to what you owe. You’ll need to weigh the lower rate against this upfront cost when deciding how much to put down.

Credit Profile and Qualification

Your credit profile serves as the foundation lenders use to price your mortgage rate. Credit scores below 680 typically push borrowers toward higher-rate products, while scores above 740 unlock access to the most competitive offerings, often 0.15% to 0.30% lower than mid-tier rates. Lenders pull reports from both Equifax and TransUnion, examining not just your score but your payment history pattern, credit utilization ratio, and length of credit relationships.

Debt service ratios matter equally. The Gross Debt Service ratio caps housing costs at 39% of gross income, while Total Debt Service ratio limits all debt payments to 44%. Exceeding these thresholds forces lenders to either decline your application or compensate for higher risk by charging premium rates. A first-time buyer carrying car loans and student debt near the 44% ceiling might face rates half a point higher than someone with minimal obligations, even with identical credit scores.

Employment stability directly affects rate eligibility. Two years of continuous employment in the same field reassures lenders; frequent job changes or gaps require additional documentation and often result in less favourable terms. Self-employed buyers face stricter scrutiny, typically needing two years of business tax returns and sometimes accepting rates 0.10% to 0.20% higher than salaried borrowers.

International buyers encounter additional hurdles. Non-residents generally need 35% down payments and face rate premiums of 0.25% to 0.50% above standard offerings, reflecting limited Canadian credit history and perceived cross-border collection risk.

Property Characteristics

Lenders scrutinize the property itself as carefully as they do your financial profile, because the home serves as collateral for the loan. A property valued at $450,000 in downtown Toronto commands different risk assessment than a $300,000 suburban townhouse, influencing both rate availability and approval terms. Location stability matters: properties in established neighborhoods with consistent appreciation patterns typically access better rates than homes in volatile or declining markets.

Condition plays a significant role in lender confidence. A well-maintained property requiring no immediate repairs signals lower risk than a fixer-upper needing extensive work. This is where presentation becomes surprisingly strategic for first-time buyers. Properties showcasing minimalist staging and professional styling often receive higher appraisal values, directly improving your loan-to-value ratio. A home appraised at $485,000 instead of $465,000 can shift you from high-ratio to conventional territory, potentially saving 0.20-0.35% on your rate, meaningful savings over a five-year term. Lenders also consider property type: single-family homes generally qualify for the most competitive rates, while condos may face slight premiums due to additional risk factors like condo corporation health and reserve fund status.

Breaking Down Your Monthly Mortgage Cost

A real estate professional and mortgage advisor reviewing documents near the front door of a home.
Professional review during a property visit reflects how qualification factors can influence what mortgage rate a buyer may receive.

Beyond the Interest Rate

Your monthly mortgage payment represents just one piece of your total housing expense. First-time buyers must budget for several additional costs that can add hundreds of dollars to monthly obligations.

CMHC insurance premiums typically range from 0.60% to 4.00% of your mortgage amount, depending on your down payment size. With less than 10% down, you’ll pay the maximum premium, $4,000 on a $100,000 mortgage, added to your principal and financed over the loan term.

Property taxes vary dramatically by location, from under $200 monthly in some regions to over $500 in high-assessment areas. Lenders often collect these through monthly payments held in escrow.

Home insurance averages $100 to $250 monthly for first-time buyers, with older properties and higher coverage limits pushing costs upward. Lenders require proof of coverage before closing.

Utilities including electricity, gas, water, and internet typically run $200 to $400 monthly. Budget an additional 1% of property value annually for maintenance and repairs, $400 monthly on a $500,000 home.

Condo buyers face monthly strata or maintenance fees covering building upkeep, amenities, and reserve funds, commonly ranging from $200 to $600 depending on building age and services included.

How to Secure the Best Rate as a First-Time Buyer

Current Lender Promotions

Lenders routinely sweeten their posted rates with limited-time promotions that can add real value beyond the headline number. RBC’s current offer, available until August 31, 2026, provides up to $5,900 in value with eligible mortgages, a package that might include cash back, fee waivers, or rate discounts. Nesto advertises a 5-year fixed insured rate at 4.09% as of July 20, while Ratehub shows competitive 3-year fixed rates as low as 3.89%.

When evaluating these promotions, calculate the total cost over your full term rather than fixating on flashy upfront bonuses. A 0.10% rate difference on a $400,000 mortgage costs roughly $400 annually, so a lower base rate often beats a one-time cash incentive. Check expiry dates, qualification requirements, and whether promotional rates apply to your specific down payment and property type. Some offers restrict professional staging expenses or appraisal fees, while others cover legal costs, details that directly affect your out-of-pocket closing costs.

Working with Professionals vs Going It Alone

The Staging Advantage in Mortgage Qualification

A professionally staged home doesn’t just sell faster, it can directly lower your mortgage rate. When a property is well-presented, appraisers often assign higher values, which improves your loan-to-value ratio and can qualify you for preferential rate tiers. A property appraised at $525,000 instead of $500,000 with the same purchase price means stronger equity position from day one, potentially shifting you from a 4.62% rate to a 4.09% rate in the current market.

First-time buyers who choose a virtual styling service before their property appraisal can influence this outcome without the expense of physical staging. Strategic placement of furnishings, the ability to mix old and new design elements, and thoughtful incorporation of aged and superior pieces all contribute to perceived value that appraisers and lenders recognize.

This staging advantage proves especially valuable when you’re close to the 20% down payment threshold. An improved appraisal can mean the difference between paying CMHC insurance premiums or avoiding them entirely, saving thousands over your mortgage term while securing a better rate.

Common Questions About First-Time Buyer Mortgage Rates

A staged living room interior with warm sunlight and a key peeking from an envelope near a coffee table.
A welcoming, well-presented interior symbolizes how home staging can support stronger appraisals and buyer confidence.

What mortgage rate can I expect with a 5% down payment?

With a 5% down payment in July 2026, you’ll qualify for an insured mortgage, which typically offers better rates than uninsured mortgages. Current insured rates range from 3.40% for a 5-year variable to 4.09% for a 5-year fixed, depending on the lender and your credit profile.

Should I choose a fixed or variable rate in 2026?

With the Bank of Canada’s policy rate at 2.25% as of July 15, 2026, variable rates currently start lower at 3.40% compared to fixed rates around 3.99%. Choose variable if you can handle payment fluctuations and believe rates will remain stable or decline; choose fixed if you prioritize budget certainty and protection against potential rate increases.

Can I negotiate my mortgage rate with lenders?

Yes, posted rates are almost always negotiable. Lenders frequently offer discounts below their advertised rates, especially if you have strong credit, a larger down payment, or are bringing multiple products to the bank. Mortgage brokers can also leverage competition between lenders to secure better terms on your behalf.

What’s the difference between insured and uninsured mortgage rates?

Insured mortgages require less than 20% down and mandatory CMHC insurance, but they typically qualify for rates 0.20% to 0.35% lower because the insurance protects lenders from default risk. Uninsured mortgages with 20%+ down carry slightly higher rates but save you the insurance premium, which can be 4% of your mortgage amount.

The qualification income you need depends on your total debt obligations, but lenders typically require that your housing costs don’t exceed 32% of your gross monthly income, and total debt payments stay under 40%. For a home requiring a monthly mortgage payment of $2,000, you’d generally need a minimum annual income around $75,000 with no other debts.

Timing your rate lock matters more than many first-time buyers realize. Most lenders offer rate holds for 90 to 120 days, protecting you if rates rise while you search for a property. This becomes particularly valuable when you’re buying a home that benefits from everlasting decor styles and professional presentation, as well-staged properties often sell faster, ensuring you complete your purchase within the rate-hold window.

The Bank of Canada’s policy rate directly influences variable mortgage rates and indirectly affects fixed rates. When the Bank adjusts its overnight rate, currently 2.25%, lenders typically adjust their prime rates within days, which immediately changes variable mortgage payments. Fixed rates respond more to bond market expectations about future rate direction rather than current policy, which explains why fixed and variable rates don’t always move in tandem.

Understanding these fundamentals helps you approach rate shopping with realistic expectations and strategic timing. First-time buyers who combine strong financial preparation with market awareness consistently secure rates toward the lower end of available ranges.

Mortgage rates for first-time buyers in 2026 span a wide range, from 3.40% on competitive variable products to over 6% for certain fixed terms, but you’re not stuck accepting whatever number appears first. Your rate isn’t random; it’s shaped by decisions you can control. A stronger credit profile, a larger down payment, and even how well your chosen property presents to appraisers all shift you toward the lower end of that spectrum and reduce your borrowing costs by thousands of dollars over the loan’s life.

This isn’t a solo endeavour. Working with mortgage brokers gives you access to multiple lenders and promotional offers that direct applications might miss. Real estate agents identify properties that fit your budget and qualification criteria. Professional staging and styling services elevate a home’s appraised value, improving your loan-to-value ratio and opening doors to better rate tiers. Each expert brings specialized knowledge that complements your research and tightens your overall strategy.

Preparation and collaboration determine whether you land a competitive rate or settle for a mediocre one. Start early, address weak points in your financial profile, and lean on professionals who understand both the mortgage landscape and the property market.

Minimalist staged living room with a vintage armchair and neutral furnishings, uncluttered surfaces, and soft natural daylight.

Why Minimalist Home Decor Is Reshaping How We Sell and Style Properties in 2026

Minimalist home decor transforms cluttered spaces into serene, functional environments by strategically removing excess and emphasizing quality over quantity. The approach centers on three core principles: intentional furniture selection, a restrained color palette anchored in neutrals, and disciplined editing of decorative objects to showcase only pieces that serve purpose or bring genuine joy.

The appeal extends beyond aesthetics. Simplified interiors reduce visual noise, creating calmer environments that many homeowners find easier to maintain and more pleasant to inhabit. For real estate professionals, minimalist staging has become a particularly effective tool because it allows potential buyers to envision their own lives in a space without the distraction of overly personalized decor. Clean lines and uncluttered rooms photograph well and tend to appeal across diverse buyer demographics.

Budget considerations matter less than many assume. Minimalism doesn’t demand expensive designer pieces or complete room overhauls. The practice often begins with what you remove rather than what you purchase. A single well-chosen vintage chair can anchor a room more effectively than three mediocre ones, and editing down existing possessions costs nothing. When new purchases are necessary, investing in fewer, higher-quality items that will endure typically proves more economical over time than cycles of disposable furniture.

The international influence on minimalist design brings valuable perspective. Scandinavian hygge emphasizes warmth within simplicity, Japanese wabi-sabi celebrates imperfection and natural materials, and European modernism contributes structural clarity. These traditions demonstrate that minimalism adapts fluidly across cultures and climates, offering flexible principles rather than rigid rules.

Successful implementation requires collaboration between vision and practicality. Homeowners benefit from understanding their actual living patterns before eliminating storage or seating, while designers and stagers must balance aesthetic restraint with the functional needs of daily life or effective property presentation.

The Core Principles Behind Minimalist Home Decor

Minimalist home decor isn’t about creating sparse, uncomfortable spaces, it’s a deliberate design philosophy built on principles that actually enhance how properties present and how people experience them. Understanding these foundations helps explain why this approach has become so valuable for staging and styling across different markets.

At its heart, minimalism operates through four interconnected principles that work together rather than in isolation:

Intentional Space Planning
Every square foot serves a clear purpose. Rooms are arranged to showcase flow and function rather than filling voids, helping potential buyers envision their own use of the space without distraction.
Functional Beauty
Objects present must justify their presence through both utility and aesthetic contribution. This dual-purpose approach eliminates decorative clutter while maintaining warmth and visual interest.
Quality Over Quantity
Fewer, well-chosen pieces create stronger impressions than numerous mediocre items. In staging contexts, this principle often reduces costs while increasing perceived property value.
Purposeful Editing
Active curation determines what stays and what goes. This ongoing process ensures spaces remain focused on their best features rather than becoming repositories for everything that might work.

These principles translate directly to staging effectiveness because they address how buyers process spaces. Uncluttered rooms photograph better and appear larger in person. Carefully selected furnishings allow architectural features to stand out rather than compete for attention. The visual calm created by edited spaces lets viewers focus on the property itself instead of getting caught up in decor choices that might not match their taste.

What separates successful minimalist staging from merely empty rooms is the balance between reduction and warmth. The goal isn’t to strip away personality but to create a foundation that feels both aspirational and livable. This requires understanding which elements contribute to that impression and which simply add noise, a distinction that becomes clearer when you’ve worked across different property types and buyer demographics.

Why Property Professionals Are Turning to Minimalist Staging

Minimalist living room staged with neutral sofa, linen accents, light wood furniture, and soft natural daylight
A calm, uncluttered living space demonstrates how minimalist staging uses negative space and warm neutrals to feel inviting.

Property professionals have discovered that minimalist staging delivers measurable advantages in today’s competitive market. When a listing features clean lines, uncluttered surfaces, and intentional space, buyers decide faster because they can immediately envision themselves in the home. The absence of personal artifacts and excessive furnishings removes cognitive barriers, allowing prospective buyers to project their own lifestyle onto the space rather than mentally editing out someone else’s.

Photography has become the primary selling tool for residential real estate, and minimalist staging translates exceptionally well through a camera lens. Rooms with fewer competing elements photograph brighter, appear larger, and maintain visual coherence across listing platforms. A well-edited space creates the picture-perfect presentation that attracts online engagement and drives showings, which matters when buyers scroll through dozens of properties before scheduling a single visit.

Minimalist staging also solves a practical problem: budget. Traditional staging often requires truckloads of furniture and accessories, storage logistics, and extended rental periods. A minimalist approach uses fewer, higher-quality pieces, reducing transportation costs and installation time. This efficiency makes professional staging accessible to a broader range of sellers and investment properties where margins matter.

The rise of remote collaboration has accelerated minimalist staging adoption. A virtual styling service can guide property professionals through minimalist transformations using video consultations, digital floor plans, and curated shopping lists. This model works particularly well for minimalist projects because the simplified aesthetic translates clearly through digital communication, there’s less room for misinterpretation when you’re working with ten carefully selected items rather than thirty.

Agents working across multiple markets have found that minimalist staging appeals to diverse buyer demographics. Young professionals appreciate the modern aesthetic, downsizers recognize the practicality, and international buyers find the neutral palette culturally adaptable. This broad appeal matters in markets where properties sit longer or attract varied buyer pools. The universality of clean, functional spaces transcends personal taste in ways that heavily styled properties cannot.

Essential Elements of Minimalist Home Styling

Color and Material Choices That Work

Start with warm neutrals as your foundation, think cream, greige, soft taupe, and pale sand rather than stark white throughout. These tones create serenity while maintaining warmth, particularly important for staging spaces where buyers need to envision themselves living comfortably. A true white ceiling paired with warmer wall tones often works better than monochrome schemes.

Natural materials prevent minimalist spaces from reading as cold showrooms. Oak, walnut, or ash flooring grounds a room with organic texture. Linen upholstery breathes better than synthetic fabrics and develops character over time. Stone countertops, marble, granite, or terrazzo, introduce subtle pattern without visual noise. Wool rugs in solid tones add tactile richness underfoot.

Layer textures rather than colors to build depth. Combine smooth plaster walls with raw timber shelving, matte ceramic vases with polished brass hardware, or woven rattan chairs with velvet cushions. The interplay between rough and refined surfaces creates interest that pure minimalism often lacks.

Introduce selective contrast through black or charcoal accents, window frames, light fixtures, or a single statement piece. This anchors the palette and prevents the washed-out effect that undermines staging impact. For properties targeting international buyers, consider how light quality varies by region; northern exposures may need slightly warmer palettes to compensate for cooler natural light.

Material quality matters more than quantity in minimalist design. One well-crafted solid wood dining table outperforms three mediocre pieces fighting for attention.

Furniture and Spatial Arrangement

Minimalist dining space with simple table styling, linen textures, and warm side lighting
Strategic furniture scale and warm lighting help a property feel functional and photogenic without visual noise.

Successful minimalist furniture choices start with a single question: does this piece earn its place? In staging, every item competes for visual attention and physical space. A low-profile sofa with clean lines can anchor a living room while making the area appear larger than traditional overstuffed seating ever could. The same principle applies to dining tables, beds, and storage units, select furnishings that serve their function without dominating the room.

Scale matters more than quantity. One substantial piece often outperforms three smaller ones fighting for relevance. A statement dining table paired with simple chairs creates impact; cluttering the same space with a buffet, bar cart, and console dilutes the effect. When positioning furniture, pull pieces away from walls. Floating a sofa eighteen inches from the wall or centering a bed in a primary bedroom demonstrates usable space rather than hiding it.

Consider sightlines from entryways. The first view into any room should reveal flow, not obstacles. Arrange furniture to guide movement through the space naturally, creating pathways that feel deliberate rather than accidental. Avoid pushing everything to the perimeter, this staging instinct actually shrinks perceived space by creating a hollow center.

Storage furniture serves double duty in minimalist schemes. A sleek credenza conceals clutter while providing surface area for a single curated vignette. Open shelving works only when ruthlessly edited, display three objects, not thirty. The goal isn’t emptiness; it’s intentional composition where each element contributes to the room’s purpose and the property’s marketability.

Adapting Minimalism to Different Property Types

Minimalist home decor works differently depending on the property type, and understanding these distinctions helps you avoid a one-size-fits-all approach that falls flat.

Urban condos benefit most from vertical emphasis and transparent furniture. Limited square footage responds well to glass tables, wall-mounted shelving, and mirrors that expand perceived space without physical clutter. A single statement piece, a sculptural chair or oversized art, provides personality while maintaining breathing room. In these compact environments, every item must earn its place through beauty or function, ideally both.

Suburban homes offer more flexibility but present a different challenge: rooms can feel sparse rather than serene if you strip too aggressively. Here, minimalism succeeds through thoughtful zoning. Define purpose for each space with intentional furniture groupings rather than filling square footage. A living room might feature one substantial sofa and two accent chairs arranged around negative space, creating conversation areas that feel deliberate rather than empty. Layering textures, linen curtains, wool throws, ceramic vessels, adds warmth without visual noise.

Luxury estates require a calibrated approach where minimalism suggests refinement rather than restraint. High-end properties succeed when you everlasting decor styles with carefully edited modern pieces. Think museum-quality art on expansive walls, architectural lighting as sculpture, and statement furniture that commands attention through craftsmanship rather than quantity. The goal isn’t emptiness but restraint that lets exceptional materials and workmanship speak.

Investment properties present budget realities that make minimalism particularly practical. Clean lines and neutral palettes photograph well and appeal broadly, reducing time on market. Focus spending on quality flooring and lighting, two elements that elevate perceived value, while keeping furniture simple and scalable. A well-chosen neutral sofa costs less than constantly refreshing trendy pieces.

International applications demand cultural sensitivity. Some markets associate sparse interiors with incompletion rather than sophistication. In these contexts, mix old and new through carefully selected traditional elements within minimalist frameworks. A single antique cabinet or regional textile grounds the space in local context while maintaining overall simplicity.

Budget considerations apply everywhere: invest in fewer, better pieces rather than filling space with compromise furniture. One excellent dining table outlasts five mediocre ones.

The Minimalist Home Decor Conversation in 2026

The conversation around minimalist home decor in 2026 happens across multiple channels, from Instagram feeds showcasing serene interiors to professional forums where agents discuss staging ROI. Industry events play a crucial role in translating online inspiration into tangible design direction, offering spaces where homeowners can experience minimalist principles firsthand and professionals can evaluate how these approaches serve real property goals.

Event Detail Information
Event The Living Luxe Design Show
Dates April 17-19, 2026
Location Toronto Congress Centre, 1020 Martin Grove Rd, Etobicoke, ON
Scale 150,000 sq. ft.
Focus Residential styling innovations including minimalist design trends

The Living Luxe Design Show, presented by JennAir Canada, represents one venue where minimalist design sits alongside broader residential styling conversations. Events like this allow property professionals to see how minimalist staging techniques compare with other approaches, assess material quality in person, and connect with styling services that execute these visions. For homeowners considering minimalist transformation, such exhibitions offer perspective on whether this aesthetic aligns with their lifestyle needs or property goals. The dialogue extends beyond any single event, social platforms, design publications, and client consultations all contribute to how minimalism evolves from trend to practical implementation strategy.

Common Pitfalls When Implementing Minimalist Design

Serene minimalist bedroom with crisp white bedding, simple lamp, and calm neutral palette
This serene bedroom scene illustrates how minimalism prioritizes calm, livability, and purposeful editing rather than emptiness.

The most common misstep in minimalist design is confusing “empty” with “intentional.” Properties stripped of all character don’t feel serene, they feel unfinished, as though staging never happened. Real minimalism curates what remains, ensuring every piece serves a purpose and contributes to the spatial narrative. When a room lacks visual anchoring points or human warmth, potential buyers disengage rather than envision themselves living there.

Over-editing presents a different problem. Some staging teams remove so much that practical living becomes unclear. A kitchen with no accessories signals “showroom” rather than “home,” and bedrooms without bedside tables or lamps raise questions about functionality. Minimalism should clarify how spaces work, not obscure their utility. Include just enough to demonstrate purpose: a bowl of fruit, a reading lamp, a throw that signals comfort without clutter.

Personality often vanishes in pursuit of neutrality. While broad appeal matters for staging, spaces need warmth to feel inviting. This is where texture becomes crucial, linen curtains, a wool rug, wood grain visible on furniture. Incorporating aged and superior pieces can ground a minimalist palette without introducing visual chaos. A single well-chosen vintage accent or artisan object adds depth that mass-produced items cannot replicate.

The most damaging misconception equates minimalism with budget staging. Simply removing furniture to avoid rental costs creates sparse, unconsidered spaces. Effective minimalist design requires deliberate selection of higher-quality pieces that command attention through form and craftsmanship. Three substantial, well-placed items outperform six mediocre ones scattered throughout a room.

Professional stylists approach minimalism by addition through subtraction, determining what belongs before considering what to remove. They understand sight lines, scale relationships, and how negative space directs attention toward architectural features or key selling points. This expertise separates minimalism as strategic design from emptiness disguised as style.

Collaborating with Professionals for Minimalist Transformation

Achieving a genuinely effective minimalist transformation rarely happens by accident. Professional styling teams bring trained eyes for spatial proportion, material quality, and the subtle details that separate austere emptiness from serene elegance. When homeowners attempt minimalist decor without guidance, they often strip away too much or fail to curate what remains, leaving spaces that photograph poorly or feel unwelcoming in person.

Working with experienced stylists offers several practical advantages. Professionals can assess which existing furnishings deserve to stay and which undermine the aesthetic, saving money by identifying quality pieces worth highlighting rather than replacing everything. They understand lighting angles and camera sightlines for property photography, ensuring that minimalist staging translates effectively across digital marketing channels. For sellers and agents working across markets, a stylist’s international perspective helps calibrate the level of minimalism appropriate for local buyer expectations without sacrificing the clean aesthetic.

Virtual consultations have expanded access to expert curation, allowing property owners anywhere to receive detailed styling plans, mood boards, and actionable shopping guidance without geographic constraints. Many professionals now offer hybrid approaches: remote planning followed by on-site installation support, or periodic virtual check-ins during phased transformations. This flexibility suits both tight timelines and budget-conscious projects.

The value of collaboration becomes especially clear when balancing minimalism with functionality. A skilled stylist helps homeowners preserve practical storage, comfortable seating, and personal warmth while editing ruthlessly elsewhere. They know which rooms demand investment pieces and where affordable alternatives work perfectly well. For properties targeting sale or lease, professionals can stage spaces that feel aspirational yet attainable, striking the balance that converts viewers into buyers.

Minimalist home decor has evolved beyond aesthetic preference to become a calculated approach to property presentation. The homes that move fastest in today’s market aren’t necessarily the most heavily styled, they’re the ones where every element earns its place, creating environments that feel both spacious and intentional.

What separates effective minimalism from simply emptying a room is understanding how space, light, and carefully chosen pieces work together to guide a buyer’s eye and imagination. This distinction matters whether you’re preparing your own home for sale, advising clients on staging strategy, or developing properties with marketability in mind. The wrong approach leaves spaces feeling stark and unwelcoming. The right approach creates clarity that helps potential buyers envision themselves in the environment.

Professional styling brings this expertise to the equation, the ability to edit thoughtfully rather than drastically, to balance emptiness with warmth, and to adapt minimalist principles across different property types and cultural contexts. It’s a collaborative process that considers both immediate presentation goals and longer-term livability.

As you evaluate properties in your own portfolio or consider how to position your home in a competitive market, the question isn’t whether minimalist principles apply, it’s how to implement them with the precision that produces results.

“Modern house exterior in Saskatoon at dusk with mortgage-related items like a calculator and paperwork placed on a porch railing, blurred neighborhood background.”

Mortgage Rates Saskatoon: How Much Will You Pay in 2026?

As of mid-2026, the best fixed mortgage rates in Saskatoon start at 4.09% for a five-year term, while variable rates range between 4.65% and 5.45%, depending on your credit profile, down payment size, and lender. These figures represent the most competitive offerings from national banks, credit unions, and mortgage brokers serving the Saskatoon market, though the rate you actually qualify for can shift by half a percentage point or more based on your financial circumstances.

Key Takeaway: Three numbers matter most for first-time Saskatoon buyers in 2026: 5% minimum down payment on homes under $500,000, 4.09% as the current best available fixed rate, and the Bank of Canada’s policy rate at 2.25%, which anchors variable-rate pricing.

The gap between advertised rates and approved rates depends on factors most borrowers don’t realize they can influence. Lenders assess your debt service ratios, employment stability, and property type before quoting a final number. A pre-construction condo attracts different pricing than a resale single-family home in Sutherland, even if the purchase price is identical. First-time buyers often assume they’ll automatically receive the lowest posted rate, but qualification hurdles related to income verification and credit history frequently push approved rates higher.

Understanding what drives mortgage pricing in Saskatoon requires looking beyond national trends. Local market conditions, including inventory levels and property presentation standards, affect how lenders evaluate risk. Homes that show well and appraise cleanly move through underwriting faster, sometimes unlocking better rate tiers. The choice between securing a rate independently or working with a mortgage broker also changes your access to exclusive lender programs and rate-hold periods, particularly in a market where timing can mean the difference between qualifying comfortably or stretching your budget.

Young couple holding house keys in a bright living room inside a new home.
A first-time buyer couple steps into a new home space, holding keys that symbolize readiness to move forward. The bright interior underscores optimism in the mortgage decision process.

Current Mortgage Rates in Saskatoon (2026)

Saskatoon home buyers in 2026 face a mortgage rate environment shaped by the Bank of Canada’s current policy rate of 2.25%, which has remained on hold as the central bank balances inflation control with economic growth. This pause has created a relatively stable backdrop for both fixed and variable mortgage products, though the rates borrowers actually secure depend on lender pricing decisions, individual qualifications, and market competition.

The best mortgage rates currently available to Saskatoon buyers show a clear pattern: variable rates sit below fixed rates across comparable terms, and five-year products offer slight advantages over three-year options. For fixed-rate mortgages, the three-year term comes in at 4.14%, while the five-year fixed rate sits marginally lower at 4.09%. On the variable side, three-year products are priced at 3.60%, and five-year variable rates drop to 3.40%. These represent the most competitive rates in the market, typically reserved for borrowers with strong credit profiles, stable income, and at least 20% down payment to avoid mortgage insurance.

Term Rate Type Rate Best Suited For
3-Year Fixed 4.14% Buyers expecting rate drops within 3 years
5-Year Fixed 4.09% Buyers prioritizing long-term payment stability
3-Year Variable 3.60% Risk-tolerant buyers seeking near-term savings
5-Year Variable 3.40% Buyers comfortable with rate fluctuation risk

The roughly 0.70 percentage point spread between fixed and variable rates reflects the premium lenders charge for rate certainty. A variable rate mortgage saves you money upfront but exposes you to potential increases if the Bank of Canada raises its policy rate in response to economic conditions. Fixed rates lock in your payment for the entire term, eliminating uncertainty but costing more initially.

First-time buyers often fixate on advertised rates without recognizing that qualification matters as much as the number itself. The rates listed here represent best-case scenarios. Your actual rate depends on your down payment size (minimum 5% required), debt-to-income ratio, credit score, employment stability, and whether you’re purchasing an owner-occupied home versus an investment property. Buyers putting down less than 20% must add mortgage default insurance premiums to their loan, which increases total borrowing costs even if the base rate remains the same.

Cost by Mortgage Type and Term

House keyring placed beside stacked money and folders on a desk.
A symbolic still life connects keys and prepared documents to the financial planning behind choosing a mortgage. It visually complements cost-focused sections without relying on text.

Fixed vs. Variable Rate Costs

Choosing between a fixed and variable rate mortgage shapes both your monthly budget and total interest paid over the term. At current 2026 rates in Saskatoon, a 5-year fixed mortgage sits at 4.09%, while a 5-year variable starts at 3.40%, a spread of 0.69 percentage points that translates to real dollars.

On a $350,000 mortgage with a 25-year amortization, the fixed rate at 4.09% means monthly payments of roughly $1,895. The variable rate at 3.40% drops that to around $1,740 monthly, a savings of $155 each month, or $9,300 over the five-year term if the variable rate holds steady. That’s the appeal: lower initial costs and more cash flow flexibility.

But variable rates move with the Bank of Canada’s policy decisions. If economic conditions shift and rates climb even 1%, your monthly payment jumps by approximately $175, erasing those savings and pushing your total borrowing cost higher. Fixed rates lock in predictability, your payment stays $1,895 regardless of what happens to the policy rate, which currently sits at 2.25%.

First-time buyers often favor fixed terms for budgeting certainty, especially when stretching to qualify. Variable suits those with income buffers who can absorb potential increases and want to capitalize on today’s lower starting point. Neither choice is inherently better; it depends on your risk tolerance and financial cushion. Run the numbers with your actual down payment and income to see which aligns with your situation.

3-Year vs. 5-Year Term Costs

Choosing between a 3-year and 5-year mortgage term in Saskatoon involves balancing immediate rate advantages against long-term stability. In 2026, the 3-year fixed rate sits at 4.14%, five basis points higher than the 5-year fixed at 4.09%. This inverted spread means locking in for longer actually costs you less upfront.

On a $350,000 mortgage with a 25-year amortization, that difference translates to roughly $10 monthly, the 5-year term carries a lower payment. Over the first three years, you’d pay approximately $360 less with the 5-year option before hitting your first renewal. The real cost consideration emerges at year three. With the shorter term, you’ll renegotiate in 2029 when rates could be materially different from today’s levels. If the Bank of Canada’s policy rate climbs from its current 2.25%, you might renew into a significantly higher environment.

The 3-year offers one strategic advantage: flexibility. If you anticipate selling, refinancing to access equity, or expect substantial income changes, paying marginally more for that earlier exit point can make sense. You avoid the potential penalties that come with breaking a longer term early.

For first-time buyers prioritizing payment certainty and simplicity, the 5-year term delivers both a lower rate and protection from rate volatility through 2031. You won’t revisit qualification stress tests or shop lenders again until you’ve built meaningful equity.

Mortgage advisor’s hands placing documents on a desk with a calculator and smartphone nearby.
A mortgage advisor’s hands and paperwork represent the rate-discussion and qualification process without showing any readable data. It visually reinforces that your final mortgage rate depends on your situation.

What Determines Your Mortgage Rate in Saskatoon

Income and Debt Considerations

Lenders qualify you through a lens sharpened by federal regulation, prioritizing underwriting based on income stability and debt load. Your gross debt service ratio (GDS) must stay below 39%, meaning housing costs, mortgage payment, property taxes, heating, can’t exceed 39% of your gross monthly income. Your total debt service ratio (TDS) caps all debt obligations, including car loans and credit cards, at 44% of gross income.

Income documentation matters as much as the number itself. Salaried employees typically need two recent pay stubs and a T4, while self-employed buyers face more scrutiny, often requiring two years of Notice of Assessment documents to verify consistent earnings. Variable income from commissions or bonuses may be averaged or discounted, affecting how much you qualify to borrow.

Existing debts reduce your borrowing capacity dollar for dollar. A $400 monthly car payment shrinks the mortgage amount you qualify for by roughly $80,000 at current rates. Lenders also apply a stress test, qualifying you at a rate roughly two percentage points higher than your actual contract rate, ensuring you can handle payment increases if rates climb.

Down Payment Impact

Your down payment size directly influences both your qualification and your total borrowing costs in Saskatoon’s 2026 market. While you can purchase with a minimum 5% down payment putting down less than 20% triggers mandatory mortgage default insurance from CMHC, Sagen, or Canada Guaranty. This insurance protects the lender but costs you: premiums range from 0.6% to 4% of your mortgage amount, added to your principal and paid over the loan’s life with interest.

Reaching the 20% threshold eliminates insurance requirements entirely, often unlocking better rate offerings from lenders who view you as lower risk. On a $400,000 Saskatoon home, a 5% down payment ($20,000) means insuring $380,000 at roughly 4% premium, $15,200 added to your mortgage. A 20% down payment ($80,000) avoids this cost completely and reduces your mortgage to $320,000, lowering monthly payments and total interest paid. Many lenders reserve their most competitive rates for insured mortgages under 80% loan-to-value, creating a sweet spot where qualifying with 10-15% down sometimes yields better terms than conventional mortgages just above 20%.

Property and Amortization Factors

The property you choose and your amortization period both shape the rate lenders offer and your long-term costs. Condos with high condo fees or older properties needing repairs can trigger lender scrutiny, sometimes resulting in slightly higher rates or lower approval amounts. Rural properties outside Saskatoon’s core may face stricter appraisal requirements. The property type matters because lenders assess risk differently for single-family homes, condos, and multi-unit dwellings.

Amortization length, how long you take to repay the mortgage, dramatically changes what you pay. A 25-year amortization at 4.09% on a $300,000 mortgage means roughly $1,576 monthly, with total interest near $172,800. Stretch that same loan to 30 years and monthly payments drop to $1,475, but total interest climbs past $231,000. Shorter amortizations save tens of thousands in interest but require higher monthly payments, which affects how much income you need to qualify.

Lenders also consider how amortization affects total interest when stress-testing your application under federal rules. Choosing a longer amortization improves cash flow today but locks you into years of additional interest expense, a trade-off worth modeling before you commit.

First-Time Buyer Qualification Requirements

Qualifying for your first mortgage in Saskatoon follows a structured federal framework that prioritizes income stability, manageable debt levels, and sufficient down payment. Lenders assess these factors systematically to determine whether you can handle mortgage payments alongside your other financial obligations.

The qualification process involves several critical checkpoints:

  1. Save your minimum down payment of 5% of the purchase price. For a $350,000 home in Saskatoon, that’s $17,500. Higher down payments improve your rate and eliminate mortgage insurance costs once you reach 20%.
  2. Calculate your gross debt service ratio, which measures your housing costs (mortgage payment, property taxes, heating, and 50% of condo fees if applicable) against your gross monthly income. Lenders typically require this to stay below 39%.
  3. Assess your total debt service ratio by adding all debt obligations, including car loans, credit cards, and student loans, to your housing costs. This combined figure must remain under 44% of your gross income for most conventional mortgages.
  4. Gather comprehensive income documentation spanning at least two years. Salaried employees need pay stubs and T4s, while self-employed buyers face stricter scrutiny requiring Notice of Assessments and financial statements.
  5. Check your credit score and history, as lenders require a minimum score of 600 for insured mortgages (those with less than 20% down). Higher scores unlock better rates. Review your credit report for errors before applying.
  6. Explore first-time buyer programs like the First Home Savings Account, which lets you save up to $40,000 tax-free for a down payment, or the Home Buyers’ Plan, allowing you to withdraw up to $60,000 from your RRSP without tax penalties.
  7. Get pre-approved before house hunting. Pre-approval locks in a rate for 90 to 120 days, clarifies your budget, and strengthens your negotiating position with sellers.

Income verification presents the biggest hurdle for many applicants. Lenders apply a stress test requiring you to qualify at either your contract rate plus 2% or 5.25%, whichever is higher. With today’s 4.09% five-year fixed rate, you’ll be tested at approximately 6.09%, meaning your income must support payments at that elevated rate even though you’ll pay the lower contracted amount.

The FHSA program deserves particular attention for 2026 buyers. You can contribute up to $8,000 annually and claim the deduction immediately, building your down payment faster than traditional savings while reducing your taxable income. Combined with the HBP, these tools can generate substantial down payment funds without requiring decades of aggressive saving.

Property type also influences qualification. Lenders scrutinize condominiums more carefully, requiring reserve fund studies and reviewing condo corporation financial health. Rural properties or those requiring significant repairs face tighter lending standards than move-in ready urban homes.

DIY Rate Shopping vs. Working with a Mortgage Broker

Saskatoon buyers have two main paths for securing a mortgage: researching and applying directly with lenders, or working with a mortgage broker who shops on their behalf. Each approach has distinct advantages and trade-offs worth considering before you commit time to the process.

The DIY route means contacting banks and credit unions directly, comparing their posted rates, and submitting applications yourself. You maintain complete control over the process, avoid any potential broker fees (though most brokers in Canada earn commission from lenders, not borrowers), and gain first-hand knowledge of mortgage qualification mechanics. This hands-on approach appeals to buyers who enjoy research and want to understand every detail of their financing.

The broker path delegates rate shopping to a licensed professional who accesses multiple lenders, including banks, credit unions, and alternative lenders not open to direct consumer applications. A good broker negotiates on your behalf, handles paperwork, and explains complex qualification scenarios based on your income, debt, and down payment situation. This proves especially valuable for first-time buyers navigating federal lending rules or those with non-traditional income sources.

Pros of DIY

  • Direct control over lender selection and communication timeline.
  • No concerns about broker bias toward certain lenders or products.
  • Deep learning experience about mortgage terms and qualification criteria.
Cons of DIY

  • Time-consuming process of contacting multiple institutions individually.
  • Limited access to lender-only wholesale rates and specialized products.
  • Risk of missing qualification nuances that affect your rate or approval.
Pros of Using a Broker

  • Access to multiple lenders and exclusive broker-only rates in one application.
  • Expert negotiation that may secure better terms than advertised rates.
  • Significant time savings, with the broker managing applications and paperwork.
Cons of Using a Broker

  • Potential bias if the broker receives higher commission from certain lenders.
  • Service quality varies widely between individual brokers and firms.
  • Less direct relationship with your actual lender during the mortgage term.

The right choice depends on your time availability, comfort with financial products, and complexity of your situation. Straightforward applications with stable employment and strong credit often succeed through either route. Buyers with self-employment income, lower down payments near the 5% minimum, or previous credit challenges typically benefit more from a broker’s specialized lender knowledge and problem-solving experience.

Many Saskatoon buyers split the difference: they research current rates like the 4.09% five-year fixed benchmark independently to establish baseline expectations, then consult a broker to see if professional access yields better terms. This hybrid approach costs nothing beyond your time and provides informed comparison.

How Home Staging Affects Your Buying Power

Professionally staged homes in Saskatoon typically sell for 5-10% above comparable unstaged properties, which directly impacts how much mortgage financing you’ll need. When you’re working with rates around 4.09% fixed or 3.40% variable, that price difference translates to thousands of dollars in borrowing costs and higher monthly payments. Understanding this dynamic helps you budget realistically and assess whether a premium-priced staged home fits your qualification limits.

Staged properties command higher prices because they reduce buyer uncertainty. A home that showcases how to mix old and new design elements or features aged styled pieces demonstrates move-in readiness and helps buyers visualize their future. This confidence often justifies stretching budgets, but it requires clear-eyed assessment of your debt-to-income ratio and available down payment.

International staging standards have elevated expectations in Canadian markets. European and Australian buyers expect refined presentation as baseline, and that influence shapes Saskatoon’s competitive landscape. Sellers who invest in everlasting decor choices and thoughtful details like a TV above fireplace positioned correctly create spaces that photograph well and show beautifully during viewings.

For buyers, this means recognizing that staged homes aren’t necessarily overpriced, they’re often priced to reflect market-ready condition. The alternative might be purchasing an unstaged property at lower cost but facing immediate renovation expenses that affect your borrowing capacity. Calculate both scenarios: the higher mortgage on a staged home versus the combined cost of a lower mortgage plus required updates. Your lender considers only the purchase price and your current financial position, not future renovation plans.

Staged living room with neatly arranged furniture and warm lighting.
A beautifully staged living room highlights how presentation can create confidence and perceived value for buyers. The warm, move-in-ready look supports why staging matters in competitive markets.

Frequently Asked Questions

What is the lowest mortgage rate available in Saskatoon right now?

As of 2026, the lowest rate is 3.40% for a 5-year variable mortgage, though individual rates depend on your credit profile, down payment, and lender. Fixed rates start at 4.09% for a 5-year term, offering payment certainty versus the lower initial cost of variable.

How much income do I need to qualify for a mortgage in Saskatoon?

There’s no single income threshold. Lenders assess your gross debt service ratio (housing costs shouldn’t exceed 39% of income) and total debt service ratio (all debts shouldn’t exceed 44% of income), so qualification depends on your specific debts, down payment size, and the property price you’re pursuing.

Can I buy a home with less than 20% down?

Yes, the minimum down payment is just 5% on homes under $500,000. You’ll need to pay mortgage default insurance with less than 20% down, which adds to your borrowing costs but makes homeownership accessible earlier, especially when combined with programs like the FHSA or HBP.

How does the Bank of Canada policy rate affect my mortgage?

The Bank of Canada’s policy rate, currently paused at 2.25%, influences the prime rate that lenders use to set variable mortgage rates. When the policy rate changes, variable rates adjust accordingly, while fixed rates respond more to bond market expectations of future policy moves.

Should I choose a fixed or variable rate mortgage?

Fixed rates give you payment certainty and protection against rate increases, ideal if you value budgeting stability. Variable rates offer lower initial costs and potential savings if rates decline, but carry risk if rates rise, your choice depends on your risk tolerance and financial flexibility.

Beyond these core questions, many Saskatoon buyers wonder about the practical timeline for mortgage approval. Pre-approval typically takes 24 to 48 hours and remains valid for 90 to 120 days, giving you a firm rate hold while you house hunt. This matters in a market where mortgage rate shifts can change your buying power by thousands of dollars.

The distinction between pre-qualification and pre-approval confuses many first-time buyers. Pre-qualification is an informal estimate based on self-reported information, while pre-approval involves credit checks, income verification, and a formal commitment from the lender. Only pre-approval carries weight in competitive offer situations.

First-time buyers often ask whether they should lock in a rate immediately or wait for potential decreases. Rate holds protect you from increases during your house search, but you can’t typically benefit from decreases without starting the approval process over. Most brokers recommend securing a hold once you’re actively shopping, especially if current rates align with your budget and you’ve found the stability of fixed rates appealing.

The interplay between your mortgage rate and property insurance requirements also generates questions. Homes with less than 20% down require mortgage default insurance through CMHC, Sagen, or Canada Guaranty, adding 2.8% to 4% of your mortgage amount. This cost gets rolled into your mortgage, so a higher rate amplifies the total interest you’ll pay on both your principal and the insurance premium, another reason why your actual rate matters significantly beyond the advertised number.

Cost by primary variable

Your mortgage rate in Saskatoon varies primarily by the term length you choose and whether you lock in a fixed rate or accept a variable one. As of 2026, a 3-year fixed mortgage sits at 4.14%, while extending to a 5-year fixed drops slightly to 4.09%, that small difference translates to real savings over time on a typical Saskatoon home. Variable rates offer more immediate relief: 3.60% for a 3-year variable and 3.40% for a 5-year variable, reflecting the Bank of Canada’s current 2.25% policy rate.

On a $350,000 mortgage with 5% down, the monthly payment difference between a 5-year fixed at 4.09% and a 5-year variable at 3.40% is roughly $230. That’s nearly $2,800 annually, enough to fund professional staging that showcases your property’s potential through timeless styling. Term length matters too: choosing a 3-year over a 5-year term means slightly higher rates now but the flexibility to renegotiate sooner if rates drop further, a trade-off worth weighing against your plans to stay in the home.

Price factors

Your mortgage rate isn’t published on a rate board, it’s calculated based on variables lenders assess when you apply. Credit score carries substantial weight: borrowers above 740 typically access advertised best rates like the current 4.09% five-year fixed, while scores below 680 often face premium pricing of 0.50% to 1.50% higher. Employment history matters equally, two years of stable income in the same field strengthens your application, whereas recent job changes or variable commission income may trigger stricter scrutiny and higher rates.

Property type introduces another pricing layer. Single-family detached homes in established Saskatoon neighbourhoods generally qualify for the lowest rates, while condos, especially in buildings with rental restrictions or incomplete reserve fund studies, can add 0.10% to 0.25%. Rental properties face even steeper premiums, typically 0.50% to 1.00% above owner-occupied rates regardless of your financial strength. Mortgage default insurance, mandatory below 20% down, actually improves your rate because it transfers lender risk to CMHC, often reducing rates by 0.15% to 0.30% compared to conventional mortgages requiring larger down payments without insurance.

Saskatoon’s mortgage landscape in 2026 offers clear opportunities for informed buyers. With 5-year fixed rates at 4.09% and 5-year variable at 3.40%, today’s environment rewards those who understand that advertised rates represent starting points, not guarantees. Your actual rate depends on how lenders assess your income stability, debt obligations, and down payment, variables entirely within your control to strengthen before you apply.

First-time buyers have particular advantages this year. The combination of accessible programs like the FHSA and HBP, along with the 5% minimum down payment threshold, means homeownership remains achievable for those who’ve prepared financially. Take time to calculate your debt-to-income ratio honestly, verify your income documentation, and determine whether reaching the 20% down payment mark makes strategic sense for avoiding insurance premiums.

Success in this market comes from collaboration. Mortgage brokers access lender networks you won’t find shopping alone, often securing better terms while handling complex qualification requirements. Similarly, understanding how home staging influences property values helps you recognize when a premium-priced home offers genuine move-in value versus inflated expectations.

Market conditions shift. The Bank of Canada’s policy decisions, economic trends, and lender competition all influence the rates available six months from now. Stay informed, monitor rate movements, and maintain your financial readiness so when the right property and the right rate align, you’re positioned to act confidently.

Contemporary living room vignette featuring a hand-thrown ceramic vase, textured natural-fiber wall sculpture, woven basket, wooden bowl, and stone tray in warm neutral tones.

Contemporary Home Decor Accessories That Transform Spaces in 2026

Contemporary home accessories in 2026 center on sculptural forms, organic materials, and nuanced neutral palettes that create visual interest without overwhelming a space. The shift from minimalism toward what designers now call “refined warmth” means accessories serve as intentional focal points rather than mere afterthoughts.

Start by anchoring each room with one statement piece. A hand-thrown ceramic vase in an irregular shape, a textured wall sculpture in natural fibers, or an architectural lighting fixture immediately establishes contemporary credibility. These investment pieces typically range from $150 to $800 and set the tone for everything else in the room.

Layer in functional accessories that display craftsmanship. Think handwoven baskets in varying heights, wooden bowls with visible grain patterns, or stone trays with organic edges. The contemporary aesthetic values pieces that tell a story of their making, where you can see the artist’s hand in slight variations and imperfections.

Balance hard and soft textures within each vignette. Pair smooth glass objects with rough linen, sleek metal frames with woven elements, polished surfaces with matte finishes. This textural conversation creates depth that photographs beautifully for listings and feels sophisticated in person.

Contemporary accessories work across budgets when you understand the principles. A $40 artisan candle holder and a $400 gallery sculpture both succeed if they share the same material honesty and sculptural quality. The key lies in editing ruthlessly. Three carefully chosen accessories create more impact than ten generic ones competing for attention.

The Evolution of Contemporary Accessories in 2026

Contemporary accessories have undergone a fundamental shift over the past few years, moving from afterthoughts that fill empty shelves to intentional design tools that define a space’s character. This transformation reflects a broader maturation of the contemporary aesthetic itself: rather than relying solely on architectural elements and furniture to create atmosphere, designers now view accessories as strategic layers that communicate sophistication, establish visual rhythm, and complete the narrative of a room.

Note: In 2026, accessories function as design anchors rather than decorative fillers, they’re selected first for their spatial impact, then for their aesthetic contribution.

The major design events of early 2026 confirmed this evolution with remarkable consistency. At Maison & Objet in Paris (January 15-19, 2026), exhibitors showcased accessories conceived as sculptural statements and textural counterpoints rather than mere embellishments. The Maison & Objet 2026 trends emphasized materiality, craft, and presence, qualities that position accessories as essential components of contemporary interiors. Just days later, IMM Cologne (January 20-23, 2026) reinforced these directions, with German and European manufacturers demonstrating how accessories bridge minimalist architecture and human warmth through carefully calibrated scale and finish.

This international perspective matters because contemporary design draws from global influences, and the accessory market reflects that cross-pollination. What we’re seeing in 2026 isn’t a single trend but a convergence: sustainable materials from Scandinavian makers, artisanal ceramics influenced by Japanese minimalism, textural weavings rooted in Mediterranean craft traditions. These pieces work together because they share underlying principles, restraint, quality, and intentionality, rather than matching aesthetics.

The upcoming High Point Market in North Carolina (October 17-21, 2026) will likely reinforce how North American designers adapt these international directions for local markets, demonstrating that contemporary accessorizing transcends geography while respecting regional preferences. The strategic approach has become universal: accessories now shape spatial perception, guide the eye, and establish emotional tone with the same deliberation once reserved for major furniture selections.

Essential Contemporary Accessory Categories for Every Space

Contemporary living room vignette with neutral sofa pillows, an abstract ceramic sculpture, and a matte ceramic floor vase
A styled contemporary living-room vignette demonstrates how textiles and sculptural accents work together to create a cohesive, modern look.

Textiles and Soft Furnishings

Contemporary textiles layer depth and warmth into minimalist frameworks through deliberate choices in texture rather than busy patterns. A linen throw in warm taupe draped over a charcoal sofa introduces tactile interest without visual noise, while velvet pillows in muted sage or terracotta provide strategic color accents that can shift seasonally. Handwoven wool rugs anchor seating areas with organic texture, their subtle variations in tone creating movement underfoot. Window treatments favor natural fabrics, sheer linen panels that filter light or heavyweight cotton drapes in neutral tones, avoiding fussy hardware in favor of sleek rods or recessed tracks that complement TV placement and architectural lines.

Budget-conscious approaches focus investment on foundational pieces like quality rugs that withstand traffic, while rotating lower-cost pillows and throws to refresh a space affordably. Mid-range textiles from established home retailers balance durability with contemporary aesthetics, whereas luxury natural fibers, Belgian linen, cashmere blends, hand-knotted silk, elevate spaces intended for long-term living or high-end staging. The key lies in mixing textures rather than relying on a single finish, creating layered sophistication that feels curated rather than matched.

Contemporary dining room with a sculptural glass pendant light, ceramic table settings, and minimalist wall art
Lighting and art elevate an everyday dining space, showing how contemporary accessories add both function and visual interest.

Sculptural and Artistic Elements

Contemporary spaces come alive when sculptural and artistic elements introduce personality without overwhelming the clean-lined foundation. Abstract sculptures in organic forms, smooth ceramics, wire compositions, geometric metal pieces, serve as focal points that draw the eye while maintaining the restrained elegance central to contemporary design. The key lies in selecting statement pieces with intention: a single substantial sculpture on a console table commands more impact than three small objects competing for attention.

Scale matters profoundly in contemporary accessorizing. Oversized art objects work beautifully in open-plan living areas where ceiling height and square footage can accommodate drama, while smaller sculptures suit intimate vignettes on shelving or side tables. Placement should respect negative space, the breathing room that prevents contemporary interiors from feeling cluttered. Position sculptural pieces where sightlines naturally land, entryway tables, fireplace mantels, or floating shelves flanking windows.

Contemporary styling encourages confidence in artistic choices. You can mix old and new by pairing a vintage bronze sculpture with sleek acrylic accents, creating layers of interest that feel curated rather than matched. The balance between boldness and restraint defines success: choose one or two statement artistic pieces per room, then support them with simpler accessories that complement rather than compete. This disciplined approach creates spaces that feel intentional, sophisticated, and genuinely contemporary.

Organic and Natural Accents

Organic materials and living elements ground contemporary spaces in nature without compromising clean aesthetics. Natural stone vessels, wooden bowls in sculptural forms, and handwoven baskets serve as textural counterpoints to sleek surfaces. Live plants, particularly sculptural specimens like fiddle-leaf figs, bird of paradise, or architectural succulents, introduce organic movement and purify air while maintaining the refined lines contemporary design demands. The key is restraint: select a few statement plantings rather than cluttering surfaces with greenery.

Material choices matter. Terracotta planters in matte finishes, ceramic vessels with organic glazes, and woven fiber accents deliver warmth without competing with a room’s focal points. Dried botanical arrangements, particularly pampas grass and preserved branches, offer low-maintenance alternatives that maintain visual interest year-round.

For real estate staging, opt for high-quality artificial plants and permanent organic materials like polished stone objects or woven pieces that require no upkeep between showings. Reserve living plants for occupied homes where owners can maintain them, or use them strategically during open houses and photography sessions before removing them. Property developers should install self-watering planters or hardy, drought-tolerant species in common areas, balancing biophilic benefits with practical maintenance realities across turnover cycles.

Corner of a contemporary room styled with a tall indoor plant and natural-texture decor on a console shelf
Natural materials and plants bring a contemporary, biophilic softness, making spaces feel alive without sacrificing modern simplicity.

Color, Texture, and Material Trends Shaping 2026

The palette of contemporary accessories in 2026 reflects a sophisticated evolution toward tactile richness and environmental consciousness. Insights from Maison & Objet (January 15-19, 2026) and IMM Cologne (January 20-23, 2026) reveal a design landscape where material authenticity trumps surface perfection, and where the interplay of texture creates visual interest within restrained color schemes.

Sustainable materials have moved from niche consideration to foundational choice. Reclaimed wood accessories, recycled glass vessels, and naturally dyed textiles appear throughout contemporary spaces, offering both ethical credibility and genuine character. These materials carry inherent irregularities, grain variations, subtle color shifts, organic imperfections, that prevent spaces from feeling sterile or overly curated. The contemporary aesthetic now embraces these authentic markers rather than concealing them.

Mixed metals continue their dominance, but 2026 brings nuance to the approach. Rather than the bold brass-meets-chrome contrasts of previous years, current applications layer warmer tones, brushed brass with antique bronze, champagne gold with weathered copper, creating depth without jarring transitions. This subtlety allows metal accents to anchor contemporary spaces without dominating them, particularly effective in accessories like candleholders, picture frames, and decorative bowls.

Natural stone has emerged as the textural hero of contemporary accessorizing. Marble, travertine, onyx, and limestone appear in accessories ranging from bookends to serving pieces, their veining and mineral deposits providing organic artistry. Designers favor unfilled travertine and honed finishes over polished surfaces, embracing the material’s natural porosity and texture. These stone pieces pair beautifully with aged superior pieces creating layered narratives within curated vignettes.

Material Aesthetic Qualities Ideal Applications Budget Range
Natural Stone Organic veining, tactile weight, mineral depth Sculptural objects, trays, bookends Moderate to high
Artisanal Ceramics Handcrafted texture, glaze variations, matte finishes Vases, bowls, decorative vessels Moderate
Mixed Metals Warm tonal layering, refined industrial edge Candleholders, frames, hardware Low to moderate
Reclaimed Wood Authentic patina, grain character, sustainability story Accent furniture, wall art, serving pieces Low to high

Artisanal ceramics represent perhaps the most significant shift in contemporary accessorizing. The hand-thrown vessel with visible throwing lines, the platter with uneven glaze pooling, the sculptural piece with intentional asymmetry, these imperfect objects inject humanity into minimalist frameworks. Neutral-toned ceramics in warm whites, soft grays, and earthy taupes dominate, their subtle variations creating visual interest without chromatic disruption.

The neutral palette itself has deepened and warmed. While stark white and cool gray remain foundational, 2026 accessories increasingly incorporate greige (gray-beige hybrids), warm putty tones, soft caramels, and muted terracotta. These warmer neutrals prevent contemporary spaces from reading as cold or institutional, particularly when layered across multiple accessory types. Strategic color appears through single statement pieces, a deep forest green vase, a burnt orange throw, rather than coordinated sets.

This material and color evolution creates contemporary elegance that transcends passing trends. By grounding accessory choices in natural materials with inherent longevity and timeless neutral palettes punctuated by considered color, these selections maintain relevance across shifting design cycles.

Accessorizing for Different Purposes: Selling, Living, and Investing

Property Staging: Accessories That Sell

When staging properties to sell faster accessories function as emotional triggers that help potential buyers envision themselves in the space. The key is selecting pieces that create warmth and sophistication without projecting a specific homeowner’s personality. Start with textiles: a cashmere-look throw in soft gray or warm beige draped over a sofa adds instant luxury for under $60, while oversized neutral pillows in varied textures (linen, cotton velvet, chunky weave) create visual interest at minimal cost.

Tip: Investing just 1-2% of a property’s listing price in strategic accessories can increase perceived value by 5-10% and reduce time on market by an average of three weeks.

Coffee table styling demonstrates professional attention to detail. A simple vignette, a sculptural bowl in matte ceramic, two hardcover design books with neutral covers, and a small arrangement of dried grasses, costs roughly $100 but signals contemporary taste. In bedrooms, quality white bedding with a single textured throw and two matching statement lamps creates hotel-like serenity. Avoid personal photographs, bold colors, or culturally specific art; instead, choose abstract prints in muted tones or simple botanical line drawings that complement any buyer’s vision while maintaining contemporary elegance.

Staged contemporary bedroom with neutral bedding, bedside lamp, and framed abstract artwork
This staging-style bedroom shows how neutral, high-impact accessories help create immediate comfort while staying broadly appealing.

Personal Styling: Reflecting Individual Identity

While staging demands broad appeal, personal styling invites homeowners to infuse contemporary spaces with meaningful artifacts that tell their story. The clean-lined contemporary framework becomes a canvas rather than a constraint, where carefully chosen accessories reveal personality without creating visual chaos.

Professional stylists approach personal accessory selection as collaborative discovery, exploring clients’ travel memories, artistic passions, and daily rituals to identify pieces that resonate authentically. A ceramicist’s collection might anchor a contemporary living room, or heirloom textiles could introduce warmth to minimalist bedrooms. The contemporary aesthetic accommodates these personal treasures when they share tonal harmony or sculptural quality with the overall design language.

Personal shopping services extend beyond simply selecting accessories to understanding how pieces will function in daily life. Does the homeowner entertain frequently, requiring conversation-starting objects? Do they seek calming environments that prioritize negative space? This individualized approach ensures accessories enhance lived experience rather than merely filling shelves, transforming contemporary spaces into deeply personal sanctuaries that still maintain the aesthetic’s signature sophistication.

Investment Properties: Durability Meets Design

Investment properties present a unique accessorizing challenge: pieces must project contemporary appeal while surviving multiple tenants and frequent cleanings. Property developers and managers benefit from selecting accessories that prioritize durability without sacrificing style, think tempered glass vases over delicate ceramic, performance fabrics in neutral tones, and metal sculptural pieces that withstand handling. This approach mirrors the principles of everlasting decor where timelessness and resilience converge. Focus investment on a few substantial pieces, a quality area rug in a forgiving pattern, substantial lamps with replaceable components, framed prints behind protective glass, rather than numerous fragile items. Budget-conscious strategies include purchasing multiples of identical accessories for quick replacement and selecting finishes that hide wear, such as matte blacks and brushed metals rather than polished surfaces that show fingerprints.

The Art of Curation: How Professionals Select and Place Accessories

Styling spaces with contemporary accessories isn’t about filling every surface. It’s about deliberate choices that guide the eye and create moments of visual interest throughout a room. At Loand Styles, our collaborative process, whether working hands-on or virtually across continents, follows principles refined through hundreds of styling projects for homeowners, agents, and developers.

Start with the rule of three, a foundational concept where objects grouped in odd numbers create more engaging compositions than pairs or even-numbered groupings. Three varying-height candlesticks on a dining table, a trio of ceramic vessels on open shelving, or three framed prints arranged vertically on a wall all feel naturally balanced without appearing too studied. This principle extends beyond literal groupings, think of three distinct textures within one vignette or three subtle color echoes across a room.

Visual weight matters as much as physical size. A single black sculptural piece carries more visual weight than three pale linen pillows, even if the pillows occupy more space. Professionals distribute this weight intentionally: balance a bold floor lamp on one side of a seating area with a gallery wall opposite, or counter a heavy console table with a substantial mirror above it. Ignoring visual weight creates spaces that feel lopsided, no matter how carefully you’ve measured.

Negative space, the breathing room between and around objects, defines contemporary styling more than the accessories themselves. When clients struggle with accessorizing, they’ve typically overcrowded surfaces. We remove half the items, and suddenly everything becomes visible. That sculptural bowl needs empty space around it to register as art rather than clutter.

The curation process professionals use follows a systematic approach:

  1. Assess sightlines from entry points and primary seating positions, noting what the eye encounters first in each space
  2. Establish focal points in each room, fireplace mantels, console tables, coffee tables, as anchoring locations for key accessories
  3. Select hero pieces first (statement sculptures, significant art, distinctive lighting) that set the room’s accessory tone
  4. Layer supporting elements that vary in height, texture, and scale around each hero piece without competing with it
  5. Step back after each addition to view the composition from multiple angles, removing anything that disrupts balance
  6. Photograph the space to identify what works and what reads as visual noise through the camera lens

This systematic approach proves especially valuable in virtual styling consultations, where Loand Styles collaborates with international clients through detailed room assessments, curated shopping lists, and placement guidance delivered remotely. The same principles that create impact in person translate through screens when applied methodically.

Creating vignettes, small, composed moments on side tables, shelves, or credenzas, requires layering with intention. Combine varying heights (a tall vase with low stack of books), mix materials (smooth glass with rough ceramic), and include one organic element (fresh stems or sculptural branch). Each vignette should feel complete yet effortless, as if these objects naturally gravitated together rather than being arranged.

Professional accessorizing recognizes that less execution time doesn’t mean less expertise. The ability to edit ruthlessly, knowing which three accessories will outperform ten mediocre ones, comes from understanding how visual principles interact with a room’s architecture, light quality, and purpose.

Budget-Conscious Contemporary Accessorizing

Contemporary styling doesn’t require luxury budgets. Strategic spending delivers high-impact results across any price point, from property staging projects with tight margins to personal styling where homeowners want to refresh gradually. The key lies in understanding where investment yields the greatest visual return and where economizing maintains quality without compromising the clean-lined aesthetic that defines contemporary design.

Invest in pieces that anchor a room and endure changing trends. Quality textiles, a handwoven wool rug, Belgian linen window treatments, or textured throws in natural fibers, form the tactile foundation that cheaper alternatives can’t replicate. These pieces wear better, photograph well for property listings, and justify their cost through longevity. Similarly, statement lighting and one significant sculptural object per room create focal points worth the expense. A well-designed ceramic vessel or abstract metal sculpture commands attention in ways that multiple smaller items never will.

Economize on accessories that layer around these investments. Affordable contemporary options abound in throw pillows, smaller ceramic pieces, and botanical accents. Mix a luxury cashmere throw with budget linen pillows in similar tones. Pair an investment art piece with inexpensive glass votives and natural wood trays. High-street retailers now offer clean-lined accessories that read contemporary when curated thoughtfully, especially in neutral palettes where material quality matters less than form and proportion.

The professional approach treats accessorizing as editing. Three carefully chosen pieces at varied price points outperform ten mediocre items at the same total cost. For staging, this means investing in versatile neutrals that work across multiple properties while rotating in fresh, budget-friendly accents for each listing. For personal projects, it means building slowly with intentional purchases rather than filling space quickly with forgettable objects. Contemporary elegance rewards restraint and strategic choices over sheer abundance, making it surprisingly accessible regardless of budget constraints.
Contemporary home decor accessories aren’t afterthoughts, they’re the defining touches that transform architectural shells into spaces that feel complete, whether you’re preparing a property for market, creating your personal sanctuary, or curating an investment that endures. These carefully chosen elements bridge the gap between impersonal and inviting, between functional and extraordinary.

At Loand Styles, we bring international design perspective and collaborative expertise to every accessorizing project. From hands-on styling sessions to virtual consultations that connect you with professional guidance regardless of location, we work alongside homeowners, real estate agents, and property developers to select contemporary accessories that achieve specific goals. Our approach combines the aesthetic insights drawn from major design events worldwide with the practical realities of your budget, timeline, and purpose.

The right contemporary accessories elevate spaces in measurable ways, increasing property appeal, expressing authentic personal style, or creating rental environments that attract and retain quality tenants. Explore how professional styling services can transform your space through the strategic art of contemporary accessorizing.